Simon Taylor✓

@sytaylor

Nerd in AI and Finance. Ranting @ https://t.co/LujBSZoV4r - Views 100% my own

5.3K Following73.2K Followers59.1K Posts
  1. Simon Taylor✓@sytaylor
    Stripe acquired OpenRouter. Ramp launched Router. Both are leaning into stablecoins. Cloud, mobile, and APIs are now table stakes, not an investable category. The next era of finance is something else.
    3528235268K
  2. Simon Taylor✓@sytaylor
    Simon Taylor
    RT @TokenizedPod: Host @sytaylor said that the Stablecoin Power Law Has an Important Exception: ⁣ ⁣ "If I look at Deel contractor payouts, they have DLUSD, and the user at the last mile is living inside that deal wallet just like they live inside a Felix wallet."⁣ ⁣ "When my user is captive in my app and I already have distribution, why would I not keep the yield in that scenario?"⁣ ⁣ "I think there is a viable use case for my own stablecoin where I can capture the yield."⁣ ⁣ "I do agree that if you have an ecosystem, then you make that token very valuable. But that can happen with very few players."⁣ ⁣ Distribution changes the economics. Once a user never leaves the app, the issuer keeps the float yield instead of passing it to a third-party stablecoin.⁣ ⁣ 🎙 Listen to the latest episode on Tokenizedpod(dot)com
    020337
  3. Simon Taylor✓@sytaylor
    Simon Taylor
    RT @robbiepetersen_: There’s a simple framework for what consumer interfaces agents will replace: Does this task induce dopamine or cortisol? The interfaces for cortisol-inducing tasks (research, planning, scheduling, commodity shopping etc) will get replaced by agents The interfaces for dopamine-inducing tasks (TikTok, instagram, X, discretionary shopping, gambling, dating apps etc) will be insulated Scrolling is still the greatest form factor for delivering refined dopamine and agents won’t change that
    0120365
  4. Simon Taylor✓@sytaylor
    I adored this thing.
    Obsolete Sony @ObsoleteSony
    In 2005, Sony Ericsson unveiled the W800, the world's first Walkman phone.
    50242.7K
  5. Obsolete Sony✓@ObsoleteSony
    In 2005, Sony Ericsson unveiled the W800, the world's first Walkman phone.
    Download
    571101.1K27.5K
  6. Simon Taylor✓@sytaylor
    Simon Taylor
    RT @soupsranjan: Jack Dorsey and Block have released a new voice model that feels fully conversational. It is small enough to run on a phone. This is going to help with customer service for sure but also scams are going to proliferate even more. Most bank fraud and scams start from a phone call Because a bank's phone number can be easily spoofed as most telcos don't support STIR/SHAKEN to authenticate callers. We have a product called Sardine Shield to help you identify scam calls. Currently the Android app is available in India but coming soon to other markets: 1. When you get a call from a phone number not in your address book, it risk rates that call based on caller reputation 2. Next week, we are releasing a version where high risk calls will be diverted to an AI model. 3. The AI model then has a conversation with the potential scammer (perhaps also using AI). 4. If we think it's a definite scam, the call is dropped else handed over to human to continue. Our app has been downloaded 50k+ times, it's free and we want more consumers using it to protect themselves. If you are in India, give it a spin. If you want early beta for the AI call diversion, comment below. Would love feedback as you try it!
    jack @jack
    We believe voice is the most natural way to interact with intelligence, so we created Dessa, the most authentic full-duplex speech model ever built. Talking with it feels like talking with a person…full of emotion, nuance, pauses, and a natural cadence.
    010367
  7. jack✓@jack
    We believe voice is the most natural way to interact with intelligence, so we created Dessa, the most authentic full-duplex speech model ever built. Talking with it feels like talking with a person…full of emotion, nuance, pauses, and a natural cadence.
    4.2K7.1K69.1K13.5M
  8. Simon Taylor✓@sytaylor
    Simon Taylor
    RT @soupsranjan: 🚨 Excited to share Sardine's latest product suite on AI Token fraud: AI Token is the new gold bar that fraudsters and nation-states steal and launder to distill their own models. Here's how Sardine helps: 1. Bank-grade "Know Your Business" (KYB) and "Know Your Consumer (KYC), so you are not onboarding shell companies set up to distill frontier models Sardine offers KYC and KYB globally. The same bank-grade technology that protects financial institutions globally from illicit activities is what you get. 2. Signup fraud: We want you to offer free trials and Token credits without losing all those credits to fraud. The same fraud prevention technology that helps the top fintechs, top crypto companies, top prediction markets and top social media companies, is what you get to protect your credits. 3. Account takeovers that lead to Token theft: We protect API keys to your models or to your 3rd party frontier labs with the same security posture as we protect crypto assets at top crypto exchanges. We have a two-tiered approach. Detect if a new IP was used to query an API key. Challenge such requests by having the user do a login (where we run our device fingerprinting). We have the fastest growing fraud device consortium (6B+ devices profiled globally). Fraud and money laundering rings have a nexus - the same rings that steal crypto, gift cards, cars, fintech wallets are the ones going after AI Tokens. 4. Card fraud: Fraudsters use stolen cards to buy AI Tokens, that they can then quickly resell. The same technology that protects the top retailers from Card fraud is what you get! Fraudsters method don't change, only what they steal changes: 2005-10: Smart TVs and physical goods 2010-15: Gift cards 2015-25: Crypto 2025: AI Tokens AI Token fraud has proliferated across the AI supply chain and impacting AI inference companies, neoclouds, AI gateways. In the last weeks alone, OpenCode, Railway, LiteLLM and many others have been impacted. We are here to protect you and to help you win back trust from your customers. Reach out. DMs open!
    070390
  9. Simon Taylor✓@sytaylor
    Your agent looks like a giant fraud and liability problem to your bank. Even if you sent it. The bank needs to know who it’s acting for and whether you approved what it’s doing. I mapped the protocols that could make this work:
    4914117128K
  10. Simon Taylor✓@sytaylor
    Tokenized deposits are internal stablecoins for banks Because "a bank" is actually lots of little banks inside a big one.
    231455.6K
  11. Simon Taylor✓@sytaylor
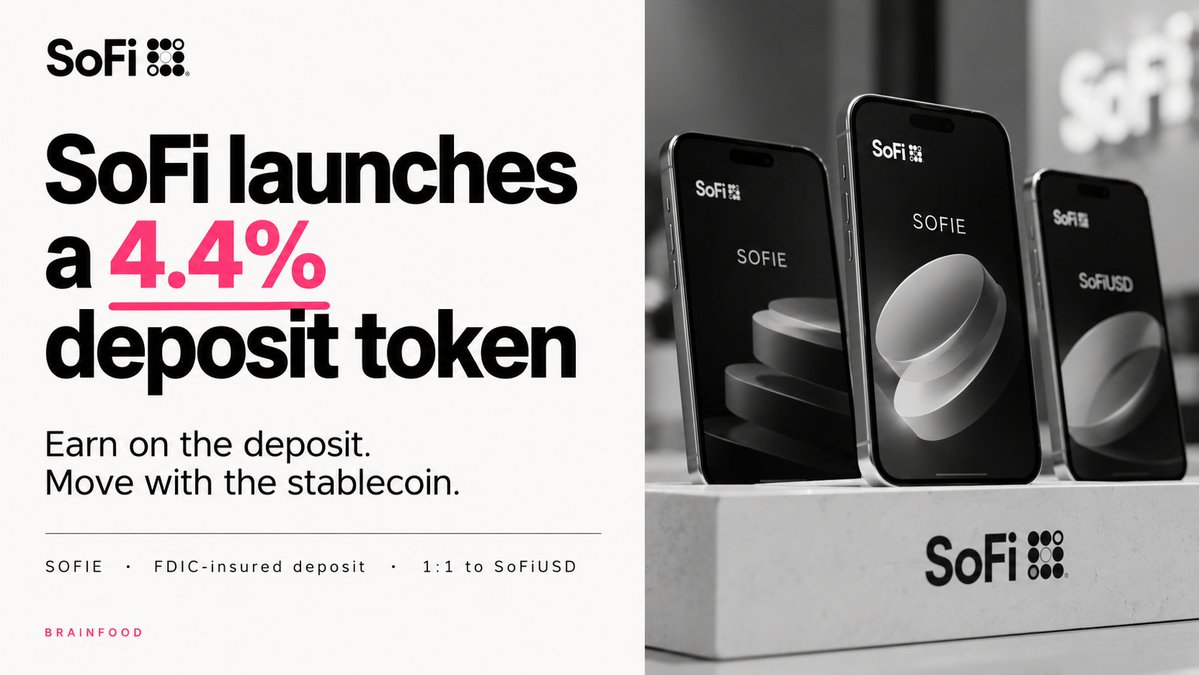
    SoFi just launched a bank deposit token that pays 4.4% and swaps into its stablecoin 24/7. And look at the timing. They announced one day after the OCC finalised the GENIUS Act rules. SoFi Earn (SOFIE) is a $1 token held as a deposit at SoFi Bank. (Kinda love that name) It's FDIC insured up to $250k, variable 4.40% APY, no minimum balance. And rolling out to SoFi Crypto members through November. --- This is not like a Stablecoin in utility. You can't send SOFIE to another person, an exchange or an external wallet. To move it, you convert 1:1 into SoFiUSD, the bank's stablecoin. The yield stops and the FDIC cover drops at that moment. GENIUS bars a stablecoin issuer from paying you anything for holding its coin. A bank deposit has no such ban. It anything it's competing with tokenized money market funds... ---- The economics work because SoFi is a lender. It funds a 4.4% deposit with double digit yields on personal loans. A stablecoin issuer earns T-bill yield on reserves and can't pass it on (or has to get very creative in how they do) --- The target is idle cash at Coinbase and in tokenized money market funds, and vs those it's competitive on rate. AND it can instantly swap either back into fiat or SoFi USD and go anywhere Stablecoins can. --- But SoFi's own savings account pays 3.3% standard. Isn't that interesting? Clearly this 4.4% is an introductory rate that they're not expecting much early use on. And that 3.3% is a cost of funding for a much bigger business. --- So here's a bull case for banks. Launch tokenized deposits. Compete with Stablecoins on yield. If customers absolutely want stablecoins you should be their on / off ramp... You hold SOFIE to earn and swap to SoFiUSD to spend. Why couldn't that work everywhere else?
    Download
    261916314.7K
  12. Simon Taylor✓@sytaylor
    Shopping is the most common use case for Muse And the average transaction size is $200
    Eric Seufert @eric_seufert
    Meta Q3 2026 earnings: interpreting early Muse metrics I don’t think I’ve ever been tagged in as many X posts as I was yesterday when Mark Zuckerberg stated on the Meta earnings call that shopping is the most common use case for Muse, and that the average Muse transaction size is $200. At first blush, this seems to undermine my 'Agentic commerce is a mirage' thesis. But I believe that deconstructing Zuckerberg's statements reveals a different interpretation. I've made my Q3 2026 earnings analysis for Meta free; no paywall.
    73446.1K
  13. Eric Seufert✓@eric_seufert
    Meta Q3 2026 earnings: interpreting early Muse metrics I don’t think I’ve ever been tagged in as many X posts as I was yesterday when Mark Zuckerberg stated on the Meta earnings call that shopping is the most common use case for Muse, and that the average Muse transaction size is $200. At first blush, this seems to undermine my 'Agentic commerce is a mirage' thesis. But I believe that deconstructing Zuckerberg's statements reveals a different interpretation. I've made my Q3 2026 earnings analysis for Meta free; no paywall.
    18815022.5K
  14. Simon Taylor✓@sytaylor
    Visa is in late-stage talks to buy Fireblocks for ~$2.5bn (Axios) That is roughly 70% below the $8bn valuation Fireblocks raised at in 2022. Fireblocks runs custody and wallet infrastructure for 2,400+ institutions, including BNY Mellon and BNP Paribas, and says it has secured over $10tn in transfers. It has become the biggest player in digital asset custody. But increasingly it's expanding in more directions and product cross-sell, while underneath, competitors like DFNS are winning market share and mind share. Fireblocks hasn't raised in a while. Visa's stablecoin settlement crossed a $20bn annualized run rate in September, up 15x in a year, with 160+ stablecoin-linked card programs live. They're arguably ahead on stablecoin-linked cards. Then Mastercard bought BVNK, Visa's settlement and OTC partner. While Fireblocks isn't a like-for-like (Visa now partners with many in that space), it does take custody, arguably a harder piece to do in-house. And the strategy here is fascinating to observe To my mind, Visa wants to be the provider of choice for any FI going onchain, especially the big banks. Fireblocks is a large book of enterprise clients and fits exactly where I think Visa is going. Cards are where stablecoins drive Visa today. As settlement for non-card payments starts to go onchain, Visa needs the wallet and custody plumbing underneath those flows. Fireblocks then looks like a logical play. Visa gets the enterprise relationships and the plumbing in one deal. Fireblocks customers now have a custody vendor owned by a card network, and some exchanges and Mastercard-aligned banks will think twice. DFNS and the rest now compete with a vendor that has Visa's sales team already inside the big banks. It reminds me that Standard Chartered also said it would take full ownership of Zodia Custody. Digital asset custody is consolidating into the incumbents. Visa paid $2bn for CyberSource in 2010 to own the e-commerce gateway. (Arguably no longer *the default* gateway, but certainly one that's very successful at least in part due to Visa's market distribution). This is that play for onchain. For Fireblocks, this is a down round and a half if it happens. But not dissimilar from what we've seen in SaaS with bending spoons. A lot of companies got bid up high in the 2021 era, and no matter how successful and how much revenue they pile on, it's still big shoes to fill. Fireblocks is a talent team, so I wish them well if this is true or not. Either way. Keep doing things. Visa and Fireblocks both sponsor tokenized, but as you'd hopefully imagine, I have no insight or color on this from either team and haven't spoken to anyone there about it.
    Download
    271612516.7K
  15. Simon Taylor✓@sytaylor
    Posts @sytaylor
    UPDATE: Fireblocks has denied this rumor or any knowledge of it!
    002556
  16. Simon Taylor✓@sytaylor
    UPDATE: Fireblocks has denied this rumor or any knowledge of it! Quite emphatically.
    Simon Taylor @sytaylor
    Visa is in late-stage talks to buy Fireblocks for ~$2.5bn (Axios) That is roughly 70% below the $8bn valuation Fireblocks raised at in 2022. Fireblocks runs custody and wallet infrastructure for 2,400+ institutions, including BNY Mellon and BNP Paribas, and says it has secured over $10tn in transfers. It has become the biggest player in digital asset custody. But increasingly it's expanding in more directions and product cross-sell, while underneath, competitors like DFNS are winning market share and mind share. Fireblocks hasn't raised in a while. Visa's stablecoin settlement crossed a $20bn annualized run rate in September, up 15x in a year, with 160+ stablecoin-linked card programs live. They're arguably ahead on stablecoin-linked cards. Then Mastercard bought BVNK, Visa's settlement and OTC partner. While Fireblocks isn't a like-for-like (Visa now partners with many in that space), it does take custody, arguably a harder piece to do in-house. And the strategy here is fascinating to observe To my mind, Visa wants to be the provider of choice for any FI going onchain, especially the big banks. Fireblocks is a large book of enterprise clients and fits exactly where I think Visa is going. Cards are where stablecoins drive Visa today. As settlement for non-card payments starts to go onchain, Visa needs the wallet and custody plumbing underneath those flows. Fireblocks then looks like a logical play. Visa gets the enterprise relationships and the plumbing in one deal. Fireblocks customers now have a custody vendor owned by a card network, and some exchanges and Mastercard-aligned banks will think twice. DFNS and the rest now compete with a vendor that has Visa's sales team already inside the big banks. It reminds me that Standard Chartered also said it would take full ownership of Zodia Custody. Digital asset custody is consolidating into the incumbents. Visa paid $2bn for CyberSource in 2010 to own the e-commerce gateway. (Arguably no longer *the default* gateway, but certainly one that's very successful at least in part due to Visa's market distribution). This is that play for onchain. For Fireblocks, this is a down round and a half if it happens. But not dissimilar from what we've seen in SaaS with bending spoons. A lot of companies got bid up high in the 2021 era, and no matter how successful and how much revenue they pile on, it's still big shoes to fill. Fireblocks is a talent team, so I wish them well if this is true or not. Either way. Keep doing things. Visa and Fireblocks both sponsor tokenized, but as you'd hopefully imagine, I have no insight or color on this from either team and haven't spoken to anyone there about it.
    51203.6K
  17. Simon Taylor✓@sytaylor
    Those Blockchain not Bitcoin boys might have had a point. What about blockchains and new assets (of which Bitcoin was one)
    Joe Weisenthal @TheStalwart
    MAYBE I WAS WRONG ABOUT BLOCKCHAIN TECHNOLOGY I wrote about how I always used to make fun of the guys who said things like "Bitcoin is speculative, but the underlying blockchain technology is interesting." And now I think maybe they kinda had a point.
    34153K
  18. Joe Weisenthal✓@TheStalwart
    MAYBE I WAS WRONG ABOUT BLOCKCHAIN TECHNOLOGY I wrote about how I always used to make fun of the guys who said things like "Bitcoin is speculative, but the underlying blockchain technology is interesting." And now I think maybe they kinda had a point.
    Download
    4223653.6K716K
  19. Simon Taylor✓@sytaylor
    Merchant economics will become an issue. Right now accepting agent payments is like accepting Amex. Expensive.
    Tom Noyes @noyesclt
    M2020. Top Recaps - Part 1. Stripe is not only the payment engine for Muse, they are actually core to Meta's economics. The 300bps linked card is providing meta with ~100bps of revenue. Card networks are enabling the economics of Agentic. This works beyond Stripe merchants, and beyond Link wallets. The linked card creates alignment with Meta and Stripe. While Stripe may be capable of creating an alternative payment network, they can't create the economics (merchant acceptance of a 300bps card for stripe and non-stripe merchants). Big retailers are set to block this card (and "wallet") due to price, most of the large merchants require customer auth with merchant. The merchant friendly solution to Muse and agent integration is form @LoginID_io. A fantastic merchant friendly integration to their Auth. Expect a presentation w/ MRC.
    251676.2K
  20. Tom Noyes✓@noyesclt
    M2020. Top Recaps - Part 1. Stripe is not only the payment engine for Muse, they are actually core to Meta's economics. The 300bps linked card is providing meta with ~100bps of revenue. Card networks are enabling the economics of Agentic. This works beyond Stripe merchants, and beyond Link wallets. The linked card creates alignment with Meta and Stripe. While Stripe may be capable of creating an alternative payment network, they can't create the economics (merchant acceptance of a 300bps card for stripe and non-stripe merchants). Big retailers are set to block this card (and "wallet") due to price, most of the large merchants require customer auth with merchant. The merchant friendly solution to Muse and agent integration is form @LoginID_io. A fantastic merchant friendly integration to their Auth. Expect a presentation w/ MRC.
    13920871.6K
  21. Simon Taylor✓@sytaylor
    Stripe is on a day 1 integration streak Incredible through delivery Clearly, all the other wallets then integrate, but there's a lot of value in being first
    Jeff Weinstein @jeff_weinstein
    Early @claudeai Duet users, Your new fancy agent can securely buy across the web using @link, with your approval. Give it a whirl and give us feedback.
    52416.5K
  22. Jeff Weinstein✓@jeff_weinstein
    Early @claudeai Duet users, Your new fancy agent can securely buy across the web using @link, with your approval. Give it a whirl and give us feedback.
    Download
    251221119.2K
  23. Simon Taylor✓@sytaylor
    Anthropic's Muse?
    Claude @claudeai
    We’re opening a research preview of Claude Duet, a new app where Claude works as a proactive agent. It comes to you with what needs your attention, completes tasks you ask of it, keeps working when you step away, and checks with you before it acts on your behalf.
    03143.8K
  24. Claude✓@claudeai
    We’re opening a research preview of Claude Duet, a new app where Claude works as a proactive agent. It comes to you with what needs your attention, completes tasks you ask of it, keeps working when you step away, and checks with you before it acts on your behalf.
    Download
    2.4K4.3K55.5K11.2M
  25. Simon Taylor✓@sytaylor
    I study both companies closely. They're not far apart in AI talent. Nubank has the most scaled, dedicated foundation model for lending in the world. Ramp has much more of a story around product velocity and AI first services like router or glass
    market participant @LaurelonCapital
    Ramp is valued at $60B at ~30x rev. Nubank is valued at $60B at ~2.5x rev. They are VERY different businesses. And this is not a knock on Ramp. Ramp is an AI winner / enterprise fintech AI neolab, with myriad innovations and advantages vs incumbents like AMEX / Brex / etc. They are just executing and taking share and winning. Nubank is (perceived as) AI neutral by the market, with credit cycle / EM risk overshadowing AI tailwinds. What if Nubank is Ramp for consumer finance, a neolab in its own right? "Advances in artificial intelligence and Nubank's low-cost operating model could enable a dramatic expansion beyond Latin America... [I envision] a global financial institution serving as many as 1 billion customers across 100 countries, operating with just 5,000 employees." - @velez_david
    42475.3K
  26. market participant✓@LaurelonCapital
    Ramp is valued at $60B at ~30x rev. Nubank is valued at $60B at ~2.5x rev. They are VERY different businesses. And this is not a knock on Ramp. Ramp is an AI winner / enterprise fintech AI neolab, with myriad innovations and advantages vs incumbents like AMEX / Brex / etc. They are just executing and taking share and winning. Nubank is (perceived as) AI neutral by the market, with credit cycle / EM risk overshadowing AI tailwinds. What if Nubank is Ramp for consumer finance, a neolab in its own right? "Advances in artificial intelligence and Nubank's low-cost operating model could enable a dramatic expansion beyond Latin America... [I envision] a global financial institution serving as many as 1 billion customers across 100 countries, operating with just 5,000 employees." - @velez_david
    116126.1K
  27. Simon Taylor✓@sytaylor
    Simon Taylor
    RT @ebloch: Insane. My dot found an $8,300 mistake in my tax return. The return was prepared by a tax firm that is best in class! People, if you’re not using ChatGPT for your Finances, you are definitely leaving money on the table.
    0110372
  28. Simon Taylor✓@sytaylor
    Simon Taylor
    RT @BackseatVC: Muse, Instinct, and Grokbot really changed agentic commerce From what we can see on @link, total transactions increased by 38x, volume by 20x in September What are people having their agents buy? Retail was the most popular, then travel, and then music and entertainment
    0110348