Jeffrey Currie 🆔++✓

@CommodMkt

Founder & CEO, Real Macro. Co-Founder & Dir. 1947 Oil & Gas. Carlyle Advisor. UChicago EPIC Chair. Non-Exec Dir, Abaxx Tech, Aleph, Borr, Energy Aspects, IPULSE

211 Following82K Followers181 Posts
  1. Jeffrey Currie 🆔++✓@CommodMkt
    I’ve recently been made aware of scammers impersonating me online and using my name to approach people about supposed investment opportunities. To be clear: I will never contact you on WhatsApp offering investment opportunities or invitations to join trading groups. The SEC is aware of these types of scams and has warned that fraudsters are increasingly impersonating investment professionals across social media and messaging platforms. If you receive something claiming to be from me that looks suspicious, please do not engage, send money or provide personal information. Report the account and verify anything through my official channels. Thank you.
    7619529.4K
  2. Jeffrey Currie 🆔++✓@CommodMkt
    Jeffrey Currie 🆔++
    RT @steve_hanke: MORE EVIDENCE THAT A COMMODITY PRICE SUPER CYCLE IS IN GEAR.
    unusual_whales @unusual_whales
    U.S. steel prices just hit their highest level in more than four years, per Bloomberg. Benchmark hot-rolled coil has jumped 52% over the past year to $1,255 a ton, a level last seen in May 2022. The reason: Trump’s tariffs are squeezing foreign supply. Steel imports fell 14% in the first nine months of 2026.
    0801.2K
  3. unusual_whales✓@unusual_whales
    U.S. steel prices just hit their highest level in more than four years, per Bloomberg. Benchmark hot-rolled coil has jumped 52% over the past year to $1,255 a ton, a level last seen in May 2022. The reason: Trump’s tariffs are squeezing foreign supply. Steel imports fell 14% in the first nine months of 2026.
    1162371.3K217K
  4. Jeffrey Currie 🆔++✓@CommodMkt
    1947 Oil & Gas is worth less than its EBITDA. @Cavendish_plc's James Midgley forecasts $84m in FY27 EBITDAX at current strip prices, against an enterprise value of just $69m and a $79m market cap, with net cash on the balance sheet. That's 0.8x EV/EBITDAX, 1.9x P/E and a forecast free cash flow yield of 67%. The bottom line: Cavendish ranks 1947 as the cheapest company in its peer group. The underlying assets are already delivering: Eugene Island 331 is back online at ~1,000 boepd net, 81% oil. Ship Shoal 198 has increased production to 1,060 boepd net, up from avg. 545 boepd in H1. Two additional offshore blocks have been secured, adding approximately 10,000 gross acres to the GoA portfolio at a lower 12.5% royalty and $260k combined bid consideration. Cavendish's price target is 19p, against 9.2p at the time of its report. Disclosure: I co-founded 1947 Oil & Gas and sit on its board. Cavendish is the company's corporate broker.
    1947 Oil & Gas Plc @1947plc
    Cavendish analysts James Midgley and James McCormack reiterate their Buy recommendation on #1947, highlighting the Company's attractive valuation at less than 1x FY27 EBITDAX. They see potential for the valuation gap to narrow as production grows and further acquisitions progress. Read Here:
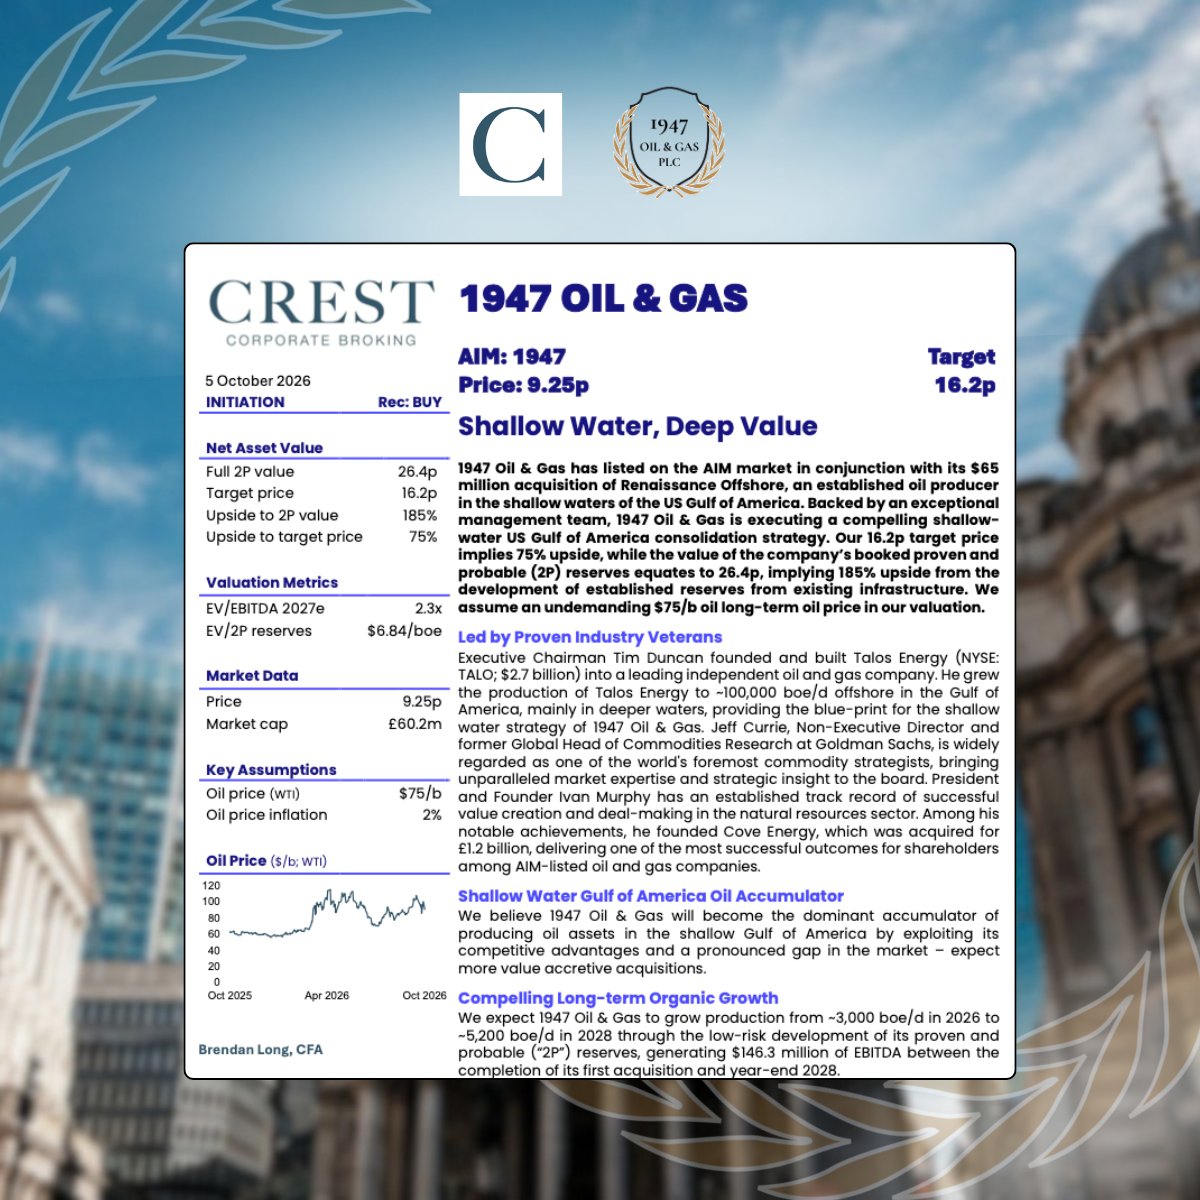
    1068016.1K
  5. 1947 Oil & Gas Plc✓@1947plc
    Cavendish analysts James Midgley and James McCormack reiterate their Buy recommendation on #1947, highlighting the Company's attractive valuation at less than 1x FY27 EBITDAX. They see potential for the valuation gap to narrow as production grows and further acquisitions progress. Read Here:
    Download
    00313.6K
  6. Jeffrey Currie 🆔++✓@CommodMkt
    Higher for longer - that was the core message in my discussion with @CNBC Squawk Box Europe this morning. Everyone is focused on the spot price of oil. But look further out: calendar 2027 Brent is holding around $97 a barrel. That’s close to $100 priced in for an entire year, not simply a short-term spike. That has implications for everything from industrial and agriculture production to transportation costs and inflation in the months ahead. Now look at energy equities. The Munificent 7 are hitting all-time highs as the back end of the oil curve approaches $100. This is looking increasingly structural, not transient. It's the Revenge of the Old Economy in action. The old economy is short-duration, asset-heavy and benefiting from higher commodity prices, whereas the new economy is long-duration, asset-light and increasingly exposed to higher interest rates and inflation. The irony in all this is that the old economy is fuelling the new economy. AI needs electricity, transformers, copper, high-voltage cables and critical minerals. None of that exists without the physical world. ‘Generalists’ in the market are beginning to recognise what specialists across the physical economy has been telling us for some time: higher for longer isn't just centred on bottlenecks and disruption to the flow of hydrocarbons out of the Strait of Hormuz. Instead, it’s a structural shift that is likely here to stay. We’re electrifying the world for many reasons, chief among them the so-called energy transition. The original driving force of the transition, led by the Carter administration, wasn’t the need to adopt clean energy with climate change in mind; it was driven by an urgent need for energy security in response to the oil shocks of the 1970s. We’re seeing a repeat today: the crisis in the Strait of Hormuz and bottlenecks elsewhere, impacting our ability to source and transport hydrocarbons, is forcing states to turn to electrification. Great discussion with @cnbcKaren and Steve Sedgwick - thank you for having me on.
    207856953.2K
  7. Jeffrey Currie 🆔++✓@CommodMkt
    Posts @CommodMkt
    Watch the discussion in full below.
    32456.6K
  8. Jeffrey Currie 🆔++✓@CommodMkt
    1947 Oil & Gas: check out Brendan Long from CREST's report. - Our production restart adds ~1,000 boe/d, ahead of expectations - He values the company on $75 WTI against spot of $103.44 and 2027 futures at $89.27. - He expects material upgrades into 2027 as strong oil pricing is recognised as structural. - CONVICTION BUY, 16.2p target, 76% upside. Read the report in full below.
    1947 Oil & Gas Plc @1947plc
    Crest Corporate Broking analyst Brendan Long, CFA, upgrades #1947 to Conviction Buy, highlighting strong operational execution. Crest also welcomes the addition of 10,000 acres on improved royalty terms, strengthening the economics of future redevelopment opportunities. Read Here:
    248717.6K
  9. 1947 Oil & Gas Plc✓@1947plc
    Crest Corporate Broking analyst Brendan Long, CFA, upgrades #1947 to Conviction Buy, highlighting strong operational execution. Crest also welcomes the addition of 10,000 acres on improved royalty terms, strengthening the economics of future redevelopment opportunities. Read Here:
    Download
    00615.2K
  10. Jeffrey Currie 🆔++✓@CommodMkt
    Jeffrey Currie 🆔++
    RT @1947plc: Energy transition is about energy security, not just the environment. At @CanoeFinancial’s CEO Series, #1947 Co-Founder & NED Jeff Currie @CommodMkt explains how reducing dependence on foreign energy supplies has driven investment in nuclear, solar and wind power, particularly in China. Become part of the 1947 Oil & gas journey:
    0202.7K
  11. Jeffrey Currie 🆔++✓@CommodMkt
    The macro repricing of energy is now underway. Check out today's move in long dated oil - that's calendar 2027 WTI. When long dated oil moves this strongly in tandem with energy equities making new ATHs, financial markets need to listen. This is not a transient spike in prompt oil. It's far more structural. Get long, buckle your seat belt, and hang on for the ride.
    Download
    984072.3K441K
  12. Jeffrey Currie 🆔++✓@CommodMkt
    It’s the revenge of the old economy, 2026 edition. That was one of my gambits when I joined David Szybunka at Canoe Financial's CEO Series in Banff to discuss why the next commodity supercycle could be more disruptive than the last. I argued that the conditions for a sudden rotation from tech into the old economy are in place, which could be compounded by the breakdown of the post-war global order. We're witnessing a structural shift driven by deglobalisation, electrification, but investors remain fixated on the asset-light economy. The AI revolution may be here to stay, but what fuels AI? It’s bits and atoms. There is no asset-light economy without energy, metals and physical infrastructure. Huge thanks to David for his phenomenal job as host, and for those who attended the talk.
    155358036.3K
  13. Jeffrey Currie 🆔++✓@CommodMkt
    Posts @CommodMkt
    Listen to our conversation in full below.
    597114.5K
  14. Jeffrey Currie 🆔++✓@CommodMkt
    You can have that one, @annmarie.  It’s a vibe contract with the vibe set in Washington. The reason it’s a vibe contract is that ICE Brent never touches a wet barrel. Instead it converges to a futures contract on Dated Bent and is cash settled, making it a derivative on a derivative. Whether Washington sold barrels is irrelevant, it is the undenied threat that matters here because it has become unpriceable risk that discourages market participants which has caused a sharp decline in open interest, creating this disconnect with reality. As we discussed earlier, the impact goes beyond pricing. Futures markets exist to help participants hedge risk and guide them on investments. When those signals become distorted, hedging becomes harder, hedgers become hesitant and physical scarcity can worsen. Washington may be focused on keeping the screen price down, but that doesn’t solve the physical shortage. It makes it worse in the end.
    Annmarie Hordern @annmarie
    First time I’ve heard Brent described as a “vibe contract”
    285638237K
  15. Annmarie Hordern@annmarie
    First time I’ve heard Brent described as a “vibe contract”
    Download
    82011845K
  16. Jeffrey Currie 🆔++✓@CommodMkt
    I joined @FerroTV and @annmarie on @Business earlier today to discuss the latest on the energy market. The global energy crisis that we’re in the midst of goes well beyond the Strait of Hormuz, where the cost of moving oil are potentially approaching $1 billion a day in additional costs. That is unsustainable. But that’s just one part of the picture - there’s disruption across the Black Sea corridor, regular strikes on Russian refining infrastructure, Houthi-inspired obstructions in the Red Sea and the Bab al-Mandab, not to mention climate-related bottlenecks including the Rhine at historic low levels and a Panama Canal that LNGs are struggling to transit. And yet: everyone remains fixated on Brent. I call Brent a "vibe contract" because its price is increasingly disconnected from the reality of the physical energy markets. Diesel is at record highs. Gasoline prices are rising. The cost of physically delivering energy is moving higher - but Brent isn't reflecting the full extent of that disruption. Why? The answer lies within price discovery. If you're a hedger facing physical exposures that are substantially above the benchmark price of Brent, how can you accurately manage that risk? The more uncertain the market is, the more difficult it is to participate in said market, and the less confidence that is generated within the futures market. That last point is absolutely key. Futures markets are critical for the market avoiding potholes that might lie ahead. They anticipate the potholes that in turn lets traders adjust their behaviour and avoid the hazard.  If the futures market isn’t operating as it should, investment is impacted, behaviours change, people fail to price risk accurately and so they cannot anticipate the pothole - they drive straight into it. It can have profound consequences on the global market. The White House may be focused on getting through the midterms in a few weeks, but I struggle to see a straightforward resolution to addressing the reality of the market right now. Watch my discussion in full below and thanks again to the team for inviting me on.
    102414924.3K
  17. Jeffrey Currie 🆔++✓@CommodMkt
    Jeffrey Currie 🆔++
    RT @SquawkCNBC: “Whether you're talking about diesel or crude oil as well as gasoline, all of these markets are getting more thinly stretched,” says Jeffrey Currie @CommodMkt.
    0702.6K
  18. Jeffrey Currie 🆔++✓@CommodMkt
    Please look at this take from @AlaliQasem on @1947plc and the recent Crest report, which is very clearly laid out.
    Qasem Al-Ali @AlaliQasem
    1/ 🧵 New AIM listing worth a closer look: @1947plc, a shallow-water Gulf of America oil producer led by the founder of Talos Energy. Crest's initiation: BUY, 16.2p target vs 9.25p. Here's what stands out 👇
    435523.2K
  19. Qasem Al-Ali✓@AlaliQasem
    1/ 🧵 New AIM listing worth a closer look: @1947plc, a shallow-water Gulf of America oil producer led by the founder of Talos Energy. Crest's initiation: BUY, 16.2p target vs 9.25p. Here's what stands out 👇
    232625.1K
  20. Jeffrey Currie 🆔++✓@CommodMkt
    Proud to see @1947plc officially join AIM. Initiation research on 1947, by Crest Corporate Broking, titled "Shallow Water, Deep Value", has been published today. The report takes a closer look at our shallow-water Gulf strategy, 1947's incredibly strong senior leadership line-up and the company's long-term potential growth. "We believe 1947 Oil & Gas will become the dominant accumulator of producing oil assets in the shallow Gulf of America by exploiting its competitive advantages and a pronounced gap in the market." On the upside, Crest states: "Our 16.2p target price implies 75% upside, while the value of the company’s booked proven and probable (2P) reserves equates to 26.4p, implying 185% upside from the development of established reserves from existing infrastructure". You can read the report in full below.
    1947 Oil & Gas Plc @1947plc
    📊 Crest Corporate Broking has published its initiation report on #1947, with a BUY recommendation and 16.2p target price, implying 75% upside. The report, authored by oil & gas analyst Brendan Long, CFA, also values 1947’s full 2P reserves at 26.4p/share. Read the new analyst report on #1947:
    556016.4K
  21. 1947 Oil & Gas Plc✓@1947plc
    📊 Crest Corporate Broking has published its initiation report on #1947, with a BUY recommendation and 16.2p target price, implying 75% upside. The report, authored by oil & gas analyst Brendan Long, CFA, also values 1947’s full 2P reserves at 26.4p/share. Read the new analyst report on #1947:
    Download
    02614.4K
  22. Jeffrey Currie 🆔++✓@CommodMkt
    Proud to be co-founder of @1947plc, now live on #AIM. First deal: 11 producing Gulf of America fields. US$346m 2P PV10 vs US$65m acquisition cost. Debt free, unhedged, cash flowing from day one. Mature Gulf barrels are systematically mispriced. We intend to own a lot more of them. Higher for longer. Ticker: 1947
    1947 Oil & Gas Plc @1947plc
    1947 Oil & Gas plc commences trading on AIM today under ticker #1947, with a market capitalisation of approximately £65.1m on Admission. The Company has completed its acquisition of Renaissance Offshore, providing exposure to immediate cash flows and a foundation upon which to build and grow a company of scale. RNS: @CommodMkt @eyemurph
    15712342.5K
  23. 1947 Oil & Gas Plc✓@1947plc
    1947 Oil & Gas plc commences trading on AIM today under ticker #1947, with a market capitalisation of approximately £65.1m on Admission. The Company has completed its acquisition of Renaissance Offshore, providing exposure to immediate cash flows and a foundation upon which to build and grow a company of scale. RNS: @CommodMkt @eyemurph
    Download
    121431.3K
  24. Jeffrey Currie 🆔++✓@CommodMkt
    Thanks to @BloombergTV and the @BSurveillance team for having me on today. We are dealing with two trades at the same time: scarcity and debasement. The scarcity trade is in commodities, while the debasement trade is in the value of money. CPI is scarcity in the numerator and debasement in the denominator. You’ve got commodity prices being pushed higher by shortages, while governments are simultaneously debasing the value of money. And look at the returns. The Quantix Commodity Index is up 48.5% YTD - the best-performing asset class of the year. Since we made the super cycle call in October 2020, it is up 242.2%, making commodities the best-performing asset class of the decade. This is why you need to own commodities. Watch the full interview here:
    125235551.4K
  25. Jeffrey Currie 🆔++✓@CommodMkt
    Thank you to @KellyCNBC and the @CNBCTheExchange team for having me on today. The old economy is taking its revenge. We are dealing with higher structural inflation after years of underinvestment in the ability to supply and deliver hard assets. There are two trades happening at the exact same time: scarcity and debasement. They actually feed on one another. War and weather are ravaging supply, while financial repression is the road to debasement. That’s toxic. We have a fuel crisis, a food crisis and copper hitting high after high. All commodities, particularly the non-energy ones, are dirt and diesel. Diesel is now the highest-price commodity on the screen. The key point is that these pressures aren’t happening in isolation. When supply is this constrained and the currency is being debased at the same time, the inflationary impact is much bigger than the headline numbers suggest. Watch the full interview here:
    187136934.9K
  26. Jeffrey Currie 🆔++✓@CommodMkt
    This is an important post from my long-time colleague @CMcgarraugh about capital efficiency and why commodities play a critical role in a portfolio. Commodities are long volatility by construction. They're spot assets such that when supply is short and inventories are exhausted, price alone rations demand through volatile price spikes. Eventually these spikes hurt financial assets, which are long-duration and short volatility. This is what creates the negative correlation. And because futures are margined, not funded, every dollar of capital buys multiples of exposure. Uncorrelated volatility plus unfunded exposure is the definition of capital efficiency. The bottom line: Commodity futures add uncorrelated volatility to a portfolio, and volatility drives capital efficiency.
    Charles McGarraugh @CMcgarraugh
    Capital Efficiency Matters If you care about long-term CAGR, you actually want volatility. Volatility means your money is working harder per unit of funding. I asked grok to compare simulated returns on two hypothetical investment strategies: 1) Sharpe Ratio = 1, volatility = 20% 2) Sharpe Ratio = 2.5, volatility = 5% Everyone thinks strategy 2 is better, and its certainly easier to hold and harder to build. But after 10 years you are between 80-90% likely to have made more money with strategy 1 than with strategy 2, depending on how correlated they are. (The more correlated their returns streams between 1 and 2, the lower the volatility of the diff, and therefore more likely you are to do better with 1) The challenge, of course, is risk managing the left tail, which is considerably easier to do with strategy (2). And TOO much volatility nearly guarantees permanent capital destruction, so you need a judicious approach. Too much leverage is a really terrible idea. Still, the point stands - for many investors it makes sense to make your money work harder by being willing to warehouse the fluctuations arising from a judicious application of dynamic leverage. This is one obvious path to better CAGR... *if* you can withstand the noise. Some nice charts from grok.
    63135980.7K
  27. Charles McGarraugh✓@CMcgarraugh
    Capital Efficiency Matters If you care about long-term CAGR, you actually want volatility. Volatility means your money is working harder per unit of funding. I asked grok to compare simulated returns on two hypothetical investment strategies: 1) Sharpe Ratio = 1, volatility = 20% 2) Sharpe Ratio = 2.5, volatility = 5% Everyone thinks strategy 2 is better, and its certainly easier to hold and harder to build. But after 10 years you are between 80-90% likely to have made more money with strategy 1 than with strategy 2, depending on how correlated they are. (The more correlated their returns streams between 1 and 2, the lower the volatility of the diff, and therefore more likely you are to do better with 1) The challenge, of course, is risk managing the left tail, which is considerably easier to do with strategy (2). And TOO much volatility nearly guarantees permanent capital destruction, so you need a judicious approach. Too much leverage is a really terrible idea. Still, the point stands - for many investors it makes sense to make your money work harder by being willing to warehouse the fluctuations arising from a judicious application of dynamic leverage. This is one obvious path to better CAGR... *if* you can withstand the noise. Some nice charts from grok.
    Download
    1711153108K
  28. Jeffrey Currie 🆔++✓@CommodMkt
    We’re in a critical situation right now - there’s no easy fix to a lack of refinery capacity, a lack of strategic reserves and products, and now-depleted crude reserves. A route to partial normalisation would be looking to China to release spare refining capacity, which seems to be happening, but a return to full normalisation is unlikely any time soon. This will shape the broader commodity and macro-economic outlook. All other commodities are dirt and diesel: we saw all time highs in copper yesterday, record-high diesel last week - we’re going to see more highs across the non-energy complex. Throughout all this, the market is obsessed with crude oil - but everyone reading this right now, as well as the rest of the world, mostly has exposure to the refined product: gasoline, diesel, jet fuel. That will hit the headline CPI index very soon. And we’ve not event talked about food - Ukrainian strikes in the grain corridors in the Black Sea, as well as weather-impacted crop yields has combined to create a food crisis alongside the fuel crisis - wheat, corn and other crops have risen sharply over the summer. Again, that will hit the headline inflation number. The bottom line: this is a crisis not only caused by the Strait of Hormuz. Chokepoints from the Red Sea to the Black Sea grain corridor, the Rhine River, the Russian interior, the Panama Canal - weather, war and policymaking - have combined to create a crisis that has no easy way out. The energy crisis is here: it has arrived and it’s showing in the product prices, not in crude. My interview on @CNBC Access Middle East with @dan_murphy can be watched in full below - thanks to Dan and team for inviting me on.
    Download
    462191K148K
  29. Show more posts