Paradis✓

@ParadisLabs

AI & tech investment research. No financial advice.

  • London
  • Joined
168 Following83.6K Followers3.9K Posts
  1. Paradis✓@ParadisLabs
    AI market colour: TLDR; Two paths forwards: 1. If stocks keep falling - HFs still hold big positions on both sides so they'd have to dump their longs and buy back their shorts at the same time. Messy messy situation. 2. If stocks turnaround higher - HFs have a large amount of AI shorts on rn, so they'd have to buy those back = short squeeze territory. So the current situation with AI stocks is that hedgies have pushed overall net exposure to the lowest level all year (latest GS PB data) with the L/S ratio for AI names near its lows. Basically, that means there's a lot of room for them to get more long (cope, but true). Across the entire book, HFs have mostly shorted against their longs rather than completely selling them, with short sales running at ~5x long buys in October MTD. That said, Tech has been hit from both sides with the record selling coming from long sales AND new shorts. FWIW, I don’t think there’s reason to panic since I highly doubt many funds out there are short the entire AI theme. A lot of the longs are now concentrated in Mag 7 which is now a record ~22% of US net exposure. So in essence, the trade has been long stable megacaps, short the rest of the AI supply chain. Funds don’t really have much room to add new long risk right now with gross already fairly elevated, so the way back for semis is by them covering shorts. A lot of the shorts recently have been put on in memory, photonics and the neoclouds, as well as Asian semis, so upside headroom is probably most significant in those areas. Time will tell. Would not try to time bottoms here.
    Download
    133134149.3K
  2. Paradis✓@ParadisLabs
    SK Hynix Earnings Call: "We believe our share price today is undervalued, not adequately reflecting our earnings and cash flow." Agreed.
    151448321.3K
  3. Paradis✓@ParadisLabs
    Foreign inflows into SK Hynix is a key watchpoint for investor sentiment now. So far this week, US investors have favoured Samsung (+$167M net bought) compares to SK Hynix (-$31M net sold). If foreign inflows into SK Hynix pick up after their stellar earnings, I think that'll be a big step in the right direction.
    719412.4K
  4. Paradis✓@ParadisLabs
    Posts @ParadisLabs
    Will update tomorrow.
    00163K
  5. Paradis✓@ParadisLabs
    Cash: $86.3B; +311% YoY Wow 😂
    Wall St Engine @wallstengine
    SK HYNIX $SKHY Q3’26 EARNINGS HIGHLIGHTS 🔹 Revenue: $78.9B (Est. $74.8B) 🟢; +328% YoY 🔹 Oper Profit: $62.8B (Est. $58.5B) 🟢; +632% YoY 🔹 Oper Margin: 80%; +3,300 bps YoY; record high 🔹 QoQ: Revenue +32% / Oper Profit +38% Q4 Guide: 🔹 DRAM Bit Growth: Mid-20% QoQ 🔹 NAND Bit Growth: Mid-single% QoQ incl. Solidigm Q3 Pricing & Volume: 🔹 DRAM ASP: High-20% QoQ; bits ~+10% QoQ 🔹 NAND ASP: Mid-20% QoQ; bits slightly lower QoQ Profitability: 🔹 Gross Margin: 85.7% (Est. 85.2%) 🟢 🔹 EBITDA: $66.1B; 84% margin; +486% YoY 🔹 EPS: $41.07; +205% YoY Financials: 🔹 Cash: $86.3B; +311% YoY 🔹 Interest-Bearing Debt: $11.9B; -34% YoY 🔹 Net Debt-to-Equity: -32%; -2,800 bps YoY 🔹 Operating Cash Flow: $41.3B; +281% YoY 🔹 Total Assets: $295.5B 2027 Market Outlook: 🔹 DRAM Demand Bit Growth: +mid-20% YoY 🔹 NAND Demand Bit Growth: +high-teens% YoY 🔹 2027 CapEx: To rise significantly vs 2026 🔸 Memory demand expected to outpace supply through 2030 Product & Technology: 🔹 HBM4: Expected to surpass HBM3E in HBM shipment and revenue share in Q4 🔹 2027 HBM: Negotiations finalized; profitability gap with conventional DRAM expected to narrow meaningfully 🔹 M15X: Ramp-up accelerating to full capacity by end-2026 🔹 321L NAND: Over 50% of domestic capacity in Q4 Business Highlights: 🔹 LTAs: Signed with 14 key customers incl. major global CSPs; standard 5-year term; over 50% of 2027-2028 capacity secured 🔹 Q3 Dividend: ~₩20,000/share (~$15.08), incl. a ₩10,000 special dividend from realized Kioxia gains 🔹 Share Acquisition: ₩20T (~$15.1B) for the quarter, incl. ~₩10T for executive & employee compensation 🔸 Quarterly revenue topped ₩100T for the first time Note: 🔹 Net Profit: $30.0B; +216% YoY 🔸 Includes a $24.6B non-operating loss: a $17.3B investment-asset loss and an $8.8B FX loss as the won strengthened FX used for USD conversion: $1 = ₩1,326 (mid-market; Oct 27, 2026)
    15825820K
  6. Wall St Engine✓@wallstengine
    SK HYNIX $SKHY Q3’26 EARNINGS HIGHLIGHTS 🔹 Revenue: $78.9B (Est. $74.8B) 🟢; +328% YoY 🔹 Oper Profit: $62.8B (Est. $58.5B) 🟢; +632% YoY 🔹 Oper Margin: 80%; +3,300 bps YoY; record high 🔹 QoQ: Revenue +32% / Oper Profit +38% Q4 Guide: 🔹 DRAM Bit Growth: Mid-20% QoQ 🔹 NAND Bit Growth: Mid-single% QoQ incl. Solidigm Q3 Pricing & Volume: 🔹 DRAM ASP: High-20% QoQ; bits ~+10% QoQ 🔹 NAND ASP: Mid-20% QoQ; bits slightly lower QoQ Profitability: 🔹 Gross Margin: 85.7% (Est. 85.2%) 🟢 🔹 EBITDA: $66.1B; 84% margin; +486% YoY 🔹 EPS: $41.07; +205% YoY Financials: 🔹 Cash: $86.3B; +311% YoY 🔹 Interest-Bearing Debt: $11.9B; -34% YoY 🔹 Net Debt-to-Equity: -32%; -2,800 bps YoY 🔹 Operating Cash Flow: $41.3B; +281% YoY 🔹 Total Assets: $295.5B 2027 Market Outlook: 🔹 DRAM Demand Bit Growth: +mid-20% YoY 🔹 NAND Demand Bit Growth: +high-teens% YoY 🔹 2027 CapEx: To rise significantly vs 2026 🔸 Memory demand expected to outpace supply through 2030 Product & Technology: 🔹 HBM4: Expected to surpass HBM3E in HBM shipment and revenue share in Q4 🔹 2027 HBM: Negotiations finalized; profitability gap with conventional DRAM expected to narrow meaningfully 🔹 M15X: Ramp-up accelerating to full capacity by end-2026 🔹 321L NAND: Over 50% of domestic capacity in Q4 Business Highlights: 🔹 LTAs: Signed with 14 key customers incl. major global CSPs; standard 5-year term; over 50% of 2027-2028 capacity secured 🔹 Q3 Dividend: ~₩20,000/share (~$15.08), incl. a ₩10,000 special dividend from realized Kioxia gains 🔹 Share Acquisition: ₩20T (~$15.1B) for the quarter, incl. ~₩10T for executive & employee compensation 🔸 Quarterly revenue topped ₩100T for the first time Note: 🔹 Net Profit: $30.0B; +216% YoY 🔸 Includes a $24.6B non-operating loss: a $17.3B investment-asset loss and an $8.8B FX loss as the won strengthened FX used for USD conversion: $1 = ₩1,326 (mid-market; Oct 27, 2026)
    Download
    852661.5K284K
  7. Paradis✓@ParadisLabs
    A lot of green in AI land today from $NBIS +11.2% to $CRDO +10.8%. Over the past few weeks, financing has been the main pressure point but it seems like we've made some solid progress this week. - $META raised $97.5B, with $60B of that coming through an ATM starting in January. - $SPCX signed a $40B deal for GPU equipment. - $AVGO set up a $63B SPV to fund custom chips for Anthropic, who also eased some fears with their S-1. Feels like the rapid de-grossing over the last few weeks has mostly run its course, however according to JPM, volumes still remain light. Interestingly, GS say that there's evidence today of "increased offense being played across the AI complex". While this is still minimal, it's a notable uptick vs. the past few weeks where risk was near zero. I wonder whether the market decides to pay attention to the upcoming hurdles, or whether it keeps riding the wall of worry higher. I personally still land on some short-term choppiness when you consider how bruised investors have gotten since July + hurdles in the next few days (hyperscaler earnings, FOMC, midterms).
    1046713.1K
  8. Paradis✓@ParadisLabs
    I spent the weekend writing an article on the current AI credit concerns. I've set myself an ambitious (and maybe unrealistic) deadline to publish it on X later today. Long-form writing & research is fun, but goodness me is it time consuming! Hopefully the more I write, the sharper my pencil becomes.
    Download
    19617925.2K
  9. Paradis✓@ParadisLabs
    Posts @ParadisLabs
    Makes sense to wait for a few hurdles to pass: - MSFT, GOOGL, AMZN earnings are big swing variables. - ORCL investor day. - FOMC
    11143.9K
  10. Paradis✓@ParadisLabs
    Which company would you hold for the next 5+ years?
    1913616.7K
  11. Paradis✓@ParadisLabs
    Quick market thoughts: Today was a dead cat bounce? Background context: Hedge funds still seem heavily underweight tech relative to consensus Q3 earnings growth. The recent unwind has flushed out crowded positioning, cut concentration and brought multiples back towards more "normal" levels across Tech/Semis. So while recent weeks have been painful for many people, I think this ultimately leaves positioning in much healthier spot to rebuild longer-term. Moving onto today specifically: Today's flows still show Tech being sold and overall very low activity levels across the board (GS). This is highly typical for the past ~month where bounces higher are mainly due to less fast/urgent selling (i.e. HFs de-grossing) rather than buyers buying.... There's nothing to suggest that risk has been added yet. That said...I do feel like we're getting close to the end of this unwind now especially with hyperscalers sticking to capex plans & Q3 semis earnings likely to be positive.
    23419729.9K
  12. Paradis✓@ParadisLabs
    Paradis
    RT @petersellis: I’m joining the team at @X to lead Product. I am a huge believer in @SpaceX's mission to extend human consciousness to the stars, so it’s time to make shitposting multiplanetary. X is the best way to find out what’s happening in the world right now and talk about it. The team has been working tirelessly to make X a better place and product for the people who love it, and many have noticed the recent momentum. My goal is to help accelerate that momentum for our community, new users, and businesses globally by continuing to make this product beautiful and useful. We are twenty years in, but it truly feels like X’s next chapter will be our greatest. I look forward to your ideas and feedback; I’m sure the replies will be measured and magnanimous.
    01.3K06K
  13. Paradis✓@ParadisLabs
    Posts @ParadisLabs
    Anthropic's S-1 naturally took priority. WIP.
    0164.6K
  14. Paradis✓@ParadisLabs
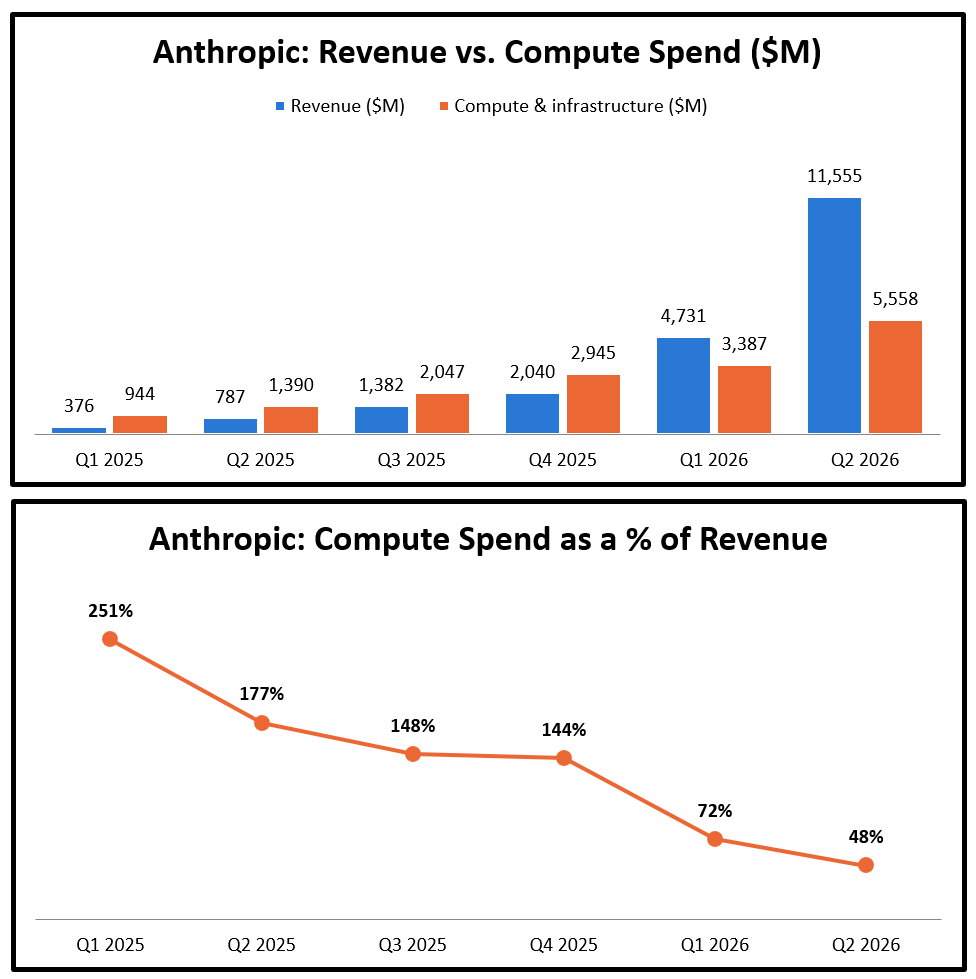
    Anthropic's S-1 shows that revenue is speeding ahead of its compute costs. > Revenue up ~31x in six quarters; compute costs up ~6x > Q1 2025: compute spend was 251% of revenue. > Q1 2026: revenue overtook compute for the first time. > Q2 2026: compute down to 48% of revenue ($5.6B vs $11.6B). Revenue from new model/product launches has more than offset Anthropic's rising compute costs. Caveat: > Bigger compute costs are coming: the SPCX deal alone is ~$3.1B/mth once fully delivered (expected Dec). > A warning in the S-1 is that margins may compress as new capacity is expensed before revenue arrives.
    Download
    131214119K
  15. Paradis✓@ParadisLabs
    Paradis
    RT @neil_shah: Nice slide. From what we can compress, thus far: @AnthropicAI : heavy on XPUs vs GPUs (very balanced) unlike OpenAI - GPU heavy + some XPUs + own silicon (small %) At annual cadence: 💰$121 Bn / yr average in compute commitments & share by silicon leased until 2033 (current by $$), adjusted per year: - NVIDIA GPU: 47% - Google TPU: 40% - AWS Trainium: 9% - AMD GPU: 4% 💰 $815B - When we include options & commitments of silicon lease for (2028-2031) period - NVIDIA GPU: 51% - Google TPU: 37% - AWS Trainium: 14% - AMD GPU: 5% solana:BTZK1B3pCoBDD1vy5e4bDBM4bwvvhkKUMTuKABkGWwGp $GOOG $NVDA
    Paradis @ParadisLabs
    Anthropic's compute and infrastructure deals. Big big numbers.
    0206K
  16. Paradis✓@ParadisLabs
    Anthropic's compute and infrastructure deals. Big big numbers.
    Download
    Anthropic @AnthropicAI
    Anthropic has filed an S-1 registration statement with the SEC related to its proposed IPO. Read more: Legal disclaimer: A registration statement relating to these securities has been filed with the SEC but has not yet become effective. These securities may not be sold, nor may offers to buy be accepted, prior to the time the registration statement becomes effective. This post does not constitute an offer to sell or the solicitation of an offer to buy these securities, nor shall there be any sale of these securities in any state or jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of any such state or jurisdiction.
    153537148.7K
  17. Anthropic✓@AnthropicAI
    Anthropic has filed an S-1 registration statement with the SEC related to its proposed IPO. Read more: Legal disclaimer: A registration statement relating to these securities has been filed with the SEC but has not yet become effective. These securities may not be sold, nor may offers to buy be accepted, prior to the time the registration statement becomes effective. This post does not constitute an offer to sell or the solicitation of an offer to buy these securities, nor shall there be any sale of these securities in any state or jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of any such state or jurisdiction.
    1.3K2.3K18K8.3M
  18. Paradis✓@ParadisLabs
    Paradis
    RT @FundaAI: 1/Anthropic’s S-1 is out. 2/ Revenue, quarter by quarter ($M) Q1'25: 376 Q2'25: 787 Q3'25: 1,382 Q4'25: 2,040 Q1'26: 4,731 Q2'26: 11,555 Q2'26 revenue was up 1,368% YoY. Compute & infra costs were up 300% over the same period. Q2'26 was the first quarter with positive GAAP operating income: $974M. 3/ How “Run-Rate Revenue” is defined Trailing-28-day consumption fees × 13 + monthly subscription fees × 12 Three caveats from the S-1: -It includes customers later found to be violating the usage policy -It is seasonal: usage dips in summer and winter holidays 4/ Revenue is recognized gross When Claude is sold through the AWS, GCP or Azure marketplaces, Anthropic is the principal. It books the full amount as revenue, and the cloud provider’s fee goes into Sales, marketing & partnerships. The marketplace share of revenue has climbed fast: 11% (2023) → 32% (2024) → 47% (2025) → 48% (H1'26) Adjust for this before comparing multiples with companies that report net. 5/ Distillation The S-1 puts a number on it: “we estimate that revenue from such customers represented approximately 5% to 7% of our revenue for the nine months ended September 30, 2026” These are customers violating the usage policy or commercial terms. Applied to ~$33B of 9M revenue, that’s roughly $1.7–2.3B. Enforcement was stepped up in Aug–Sep, and the company expects the share to decline. The S-1 says the estimate “requires judgment and may change.” 6/ Visibility is low RPO at 6/30/26: $10.8B ~75% of that is recognized in the next 12 months, so cRPO ≈ $8.1B Deferred revenue: $1.65B Q2 annualized revenue is ~$46B, so cRPO covers less than 20% of it. 80% of revenue is consumption-based, and next year’s revenue depends almost entirely on usage. 7/ The compute bill Disclosed commitments: Broadcom TPU leases: ~$161B SpaceXAI (NVIDIA GPUs): up to $121B, ~$3.1B a month from Dec’26 Google: ≥$115B, plus $125–150B more of TPU capacity in 2028–31 Amazon: ≥$110B Microsoft: ≥$45B Nscale: ~$45B Lambda: ~$41B AMD: >$20B That adds up to roughly $780–810B. 8/ The mismatch to watch Revenue is variable and consumption-driven. Compute costs are fixed, multi-year and take-or-pay. On top of that, the Broadcom leases, the credit agreement and the convertible notes include cross-default provisions. This is the single most important risk in the filing. 9/ Demand is real NRR ~900% (ex-Pro/Max) Customers paying more than $100K / $1M / $10M a year: 11,900+ / 1,900+ / ~250 No single customer was >10% of 9M’26 revenue Top 5 customers ≈ 25% of 9M revenue Q3: 79% of revenue came from outside the top 5, up from 64% in Q1 Claude Enterprise users who also use Claude Code spend ~20x more than those who don’t 10/ Dilution $77B of convertible capacity: Google $20B, Amazon $15B, Broadcom $42B, settled in shares at a trailing VWAP Google can buy up to $10B more stock at the IPO price A Public Benefit Fund already holds 5% of fully diluted shares, and can get up to +2% more for every 50% rise in the share price
    09005.5K
  19. Paradis✓@ParadisLabs
    🚨 BREAKING: Anthropic have released their S-1
    Download
    41017030.3K
  20. Paradis✓@ParadisLabs
    Posts @ParadisLabs
    ...Anthropic's S-1 is rumoured for release later today... AI credit may need to take a backseat. Great timing lol.
    00134K
  21. Show more posts