Posts with #Backtesting

#Backtesting

Public posts on X that use #Backtesting.

Related hashtags

  1. Jason✓@3PeaksTrading
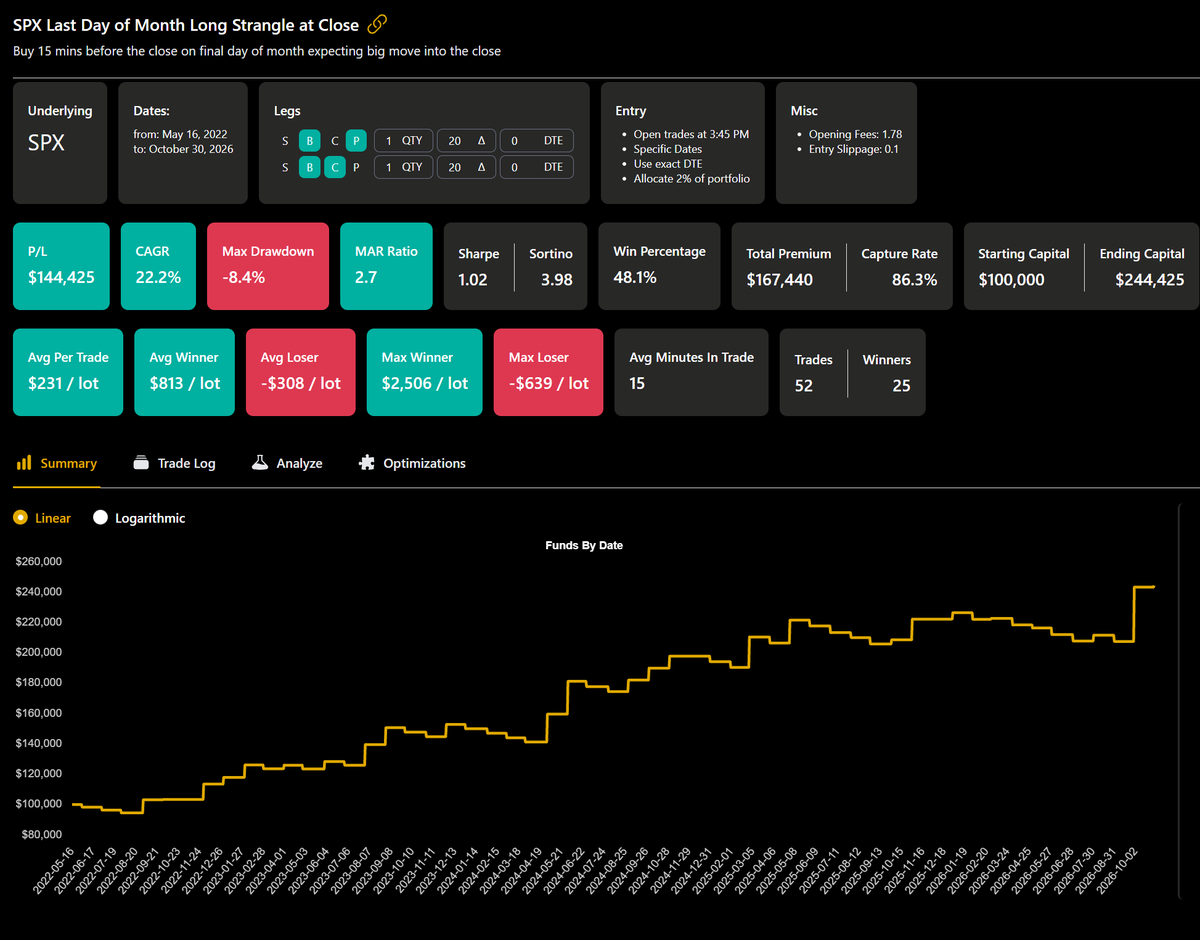
    Has some questions to share the link to the backtest for this Last day of Month long strangle that I do and it worked again yesterday. Essentially buying 20 delta put/call strangle with 15 minutes left on final day of month. Holding til close on SPX. Can see its win rate is about half the time but hugely profitable as the outlier crazy moves pay. And best part is you can automate this strategy in Option Omega to have it run each month. Can also see each year since 2022 has been profitable. A very fascinating one trade a month strategy so wanted to share
    Download
    10102.9K
  2. PropQuantX✓@PropQuantX
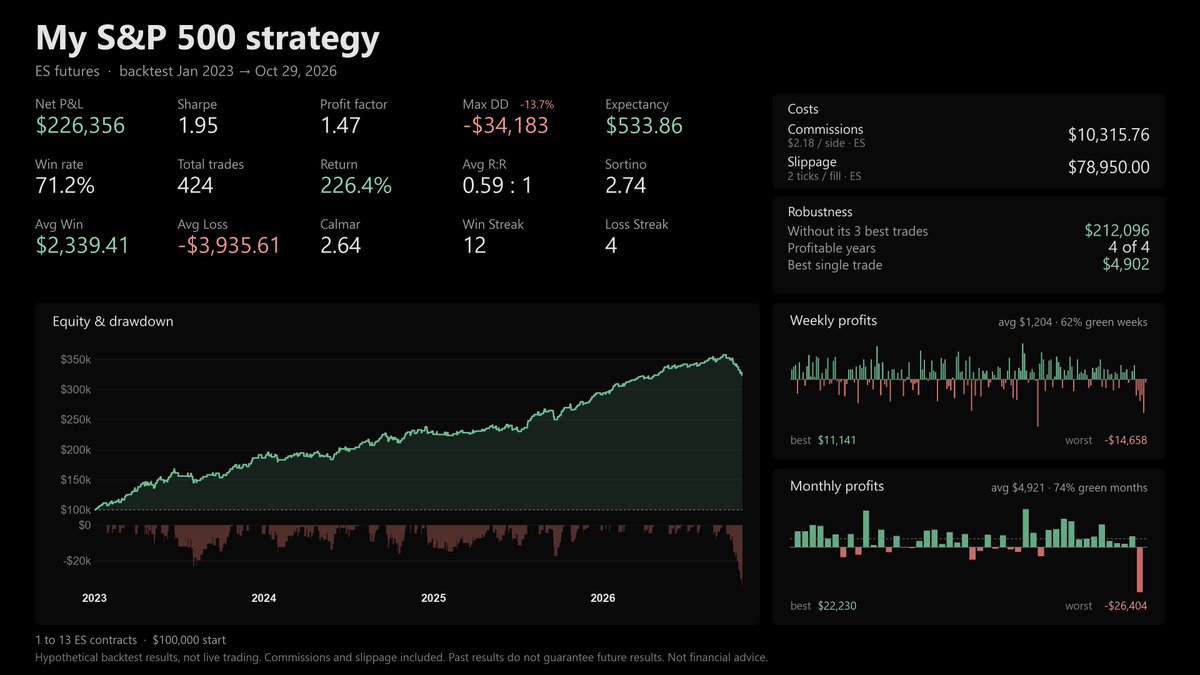
    One of my strategies is in the deepest drawdown ever. It's down $31,510 from its September high. It did very well on the OOS data and I have been running it LIVE for months with good results, until recently when it just fell of a cliff. When do you cut a strategy that goes deeper in drawdown than the backtest ever showed?
    Download
    3010944
  3. SilverTrade✓@silvertrade
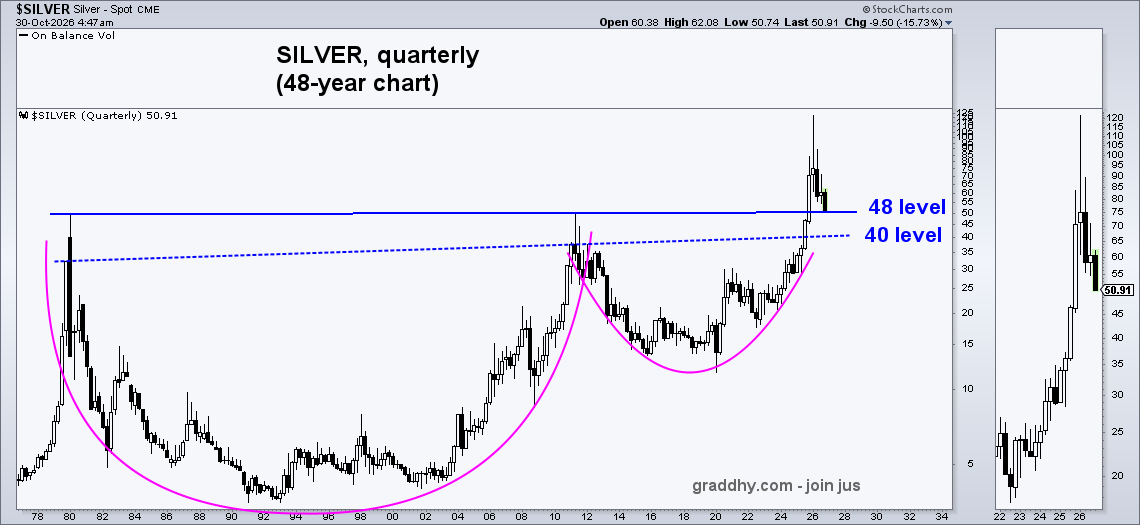
    🚨SILVER BACKTEST IN PROGRESS Silver is now BACKTESTING its massive 50-year cup-and-handle breakout which saw prices explode to over $121 in only 2 months:
    Download
    Graddhy - Commodities TA+Cycles @graddhybpc
    Silver is now at the wicks line support level on quarterly, below. And, it is now below the support line on monthly. At the service, we have been expecting this move towards 48 level. The possible backtest is now in progress.
    7713412.1K
  4. Graddhy - Commodities TA+Cycles✓@graddhybpc
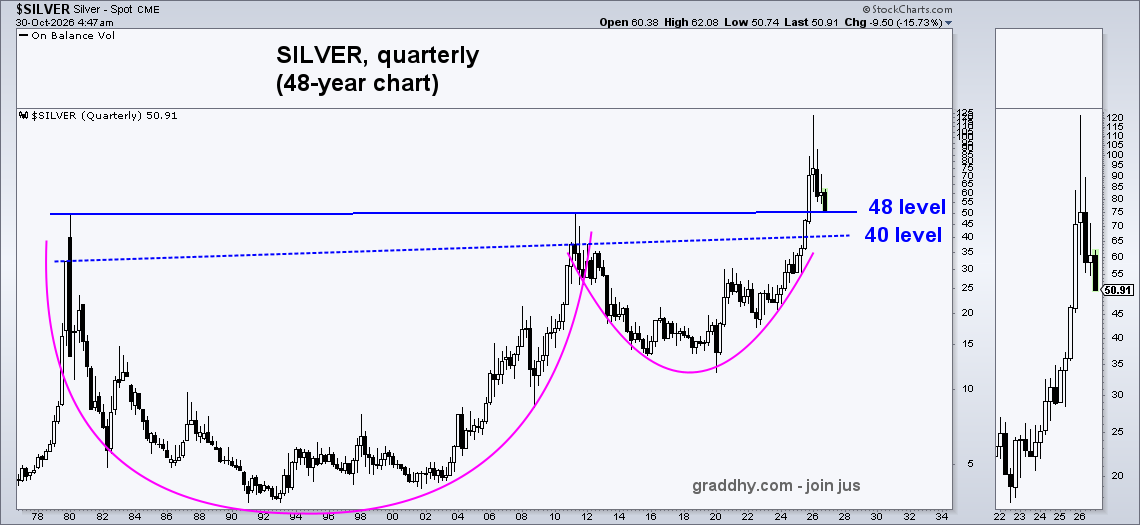
    Silver is now at the wicks line support level on quarterly, below. And, it is now below the support line on monthly. At the service, we have been expecting this move towards 48 level. The possible backtest is now in progress.
    Download
    297465259.2K
  5. Will O'Hara, CMT✓@WillOHara131
    $GOOGL −12.6% on earnings week, broke down from the 314–364 range and lost every weekly MA 📉 Lower highs: 408 → 384 → 364. Weekly RSI 33, lowest since Apr '25. 🟡 Must hold 271.8 (Mar low, last higher low) 🟢 Reclaim 295.5 → backtest 314.7–336.9 🔴 Close < 271.8 → 235–261 When are you buying GOOGL?
    Download
    204355
  6. Jack Farley✓@JackFarley96
    This was literally the top Extreme memory shortage has weighed upon AI stocks instead of boosting them... market is pricing it as unsustainable because investors think there is literally not enough money It's reflexive
    Jack Farley @JackFarley96
    The plan: we kill all of our customers Micron $MU
    1147812.7K
  7. Jack Farley✓@JackFarley96
    The plan: we kill all of our customers Micron $MU
    Download
    024827.6K
  8. Jack Farley✓@JackFarley96
    @JackFarley96
    *was the actual day of the top in Micron, the top in semi index was a few days earlier and by top I mean top "so far" it is not my base case that June was the peak of this cycle although that is of course possible obviously a humbling month for my bull view on semis (I was wrong on short-term basis) Modeling a strategy I run on backtest if we ARE in a dot com crash my strategy isn't as bad as one might think however backtesting Fama French index back to 1929 losses are catastrophic however that is very unlikely but possible there really are only two strategies mean those that bet on mean reversion and those that bet on continued trend and the issue with mean reversion strategies is they always are the most appealing the more the trade moves against you as it happens although MY view has been demolished this month the content on my media company w/ @maxwiethe Monetary Matters actually has had lots of caution over past 3-4 months that has aged pretty well
    20183.1K
  9. fundlabz@fundlabz
    12 trades is not a strategy. It's a coincidence with a chart. 30 is the minimum before the math means anything — and your tester should tell you that. #backtesting
    Download
    00238
  10. Сarm1ne✓@carm1nee
    🚨these github repos is SERIOUSLY DANGEROUS Wall Street pays its engineers $500K+ a year to write code like this, 6 of the top firms put theirs on GitHub 6 repos built inside Goldman Sachs, JPMorgan, Jane Street, Jump, Morgan Stanley and Man Group, with 38.6k stars combined First, get how it works: 1. Goldman Sachs' quants built gs-quant for pricing, risk and backtesting. JPMorgan's python-training is the exact course it uses to train its own traders and analysts. 2. Jane Street's magic-trace traces every function call at ~40ns. Morgan Stanley's Xpedite profiles low-latency trading code, "where latency directly translates to profitability". Jump's Firedancer runs Solana on a design taken from low-latency trading. 3. Man Group's ArcticDB stores and queries market data across billions of rows. Together it's a full desk: data, research, risk and speed. Here's how you can run it for free yourself: 1. Open Claude Code and start with JPMorgan's trader course, python-training. Have Claude run the notebooks with you 2. Install Goldman Sachs' library: pip install gs-quant 3. Add the skill that teaches Claude Code to use it: python -m gs_quant.skills install --global 4. Have Claude pull 5 years of daily prices for GS, JPM and MS with free yfinance data 5. Store it in Man Group's database: pip install arcticdb 6. Run Goldman's risk math on it: volatility, max drawdown, z-score, beta to SPY. Then backtest one rule with fees. Claude writes the code and runs it 7. On Linux, trace your backtest with Jane Street's magic-trace and see where every microsecond goes 8. Moving to C++? Measure every critical path the Morgan Stanley way with Xpedite 9. Have Claude walk you through how Jump built Firedancer's pipeline (net, verify, dedup, pack, bank), then apply the same ideas to your bot i won't say anything more:
    Download
    Сarm1ne @carm1nee
    these 10 GitHub repos are the most DANGEROUS thing in trading right now together they give you a full AI hedge fund: a research desk, an investment committee and an execution desk in this article I've shown EXACTLY how to build it from scratch
    1612983458.4K
  11. Сarm1ne✓@carm1nee
    these 10 GitHub repos are the most DANGEROUS thing in trading right now together they give you a full AI hedge fund: a research desk, an investment committee and an execution desk in this article I've shown EXACTLY how to build it from scratch
    3769450447K
  12. QuantifiedStrategies.com✓@QuantifiedStrat
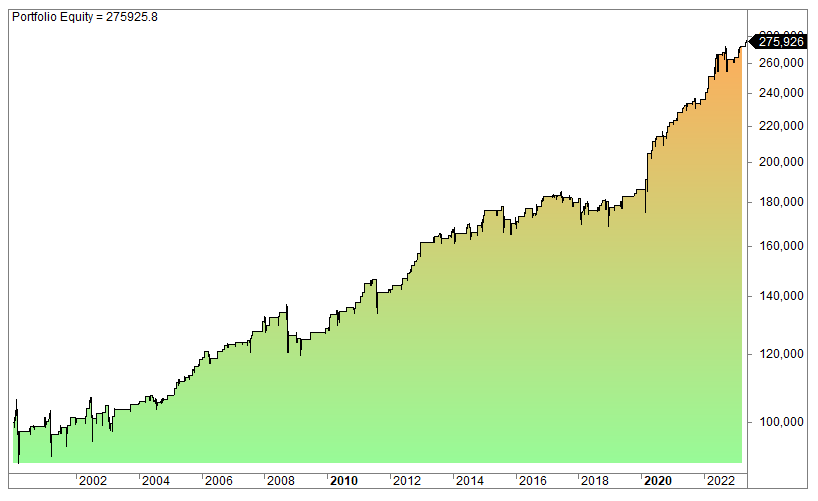
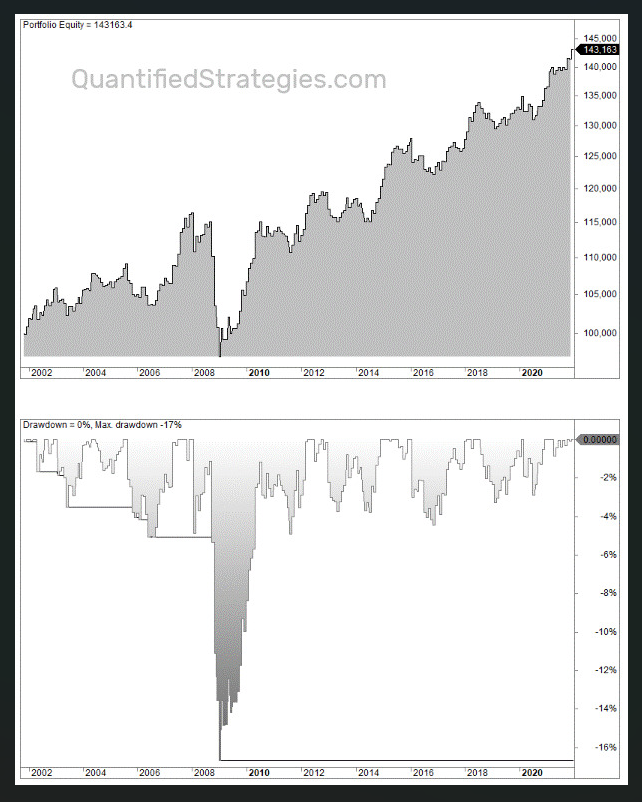
    MACD and RSI Strategy – 81.41% Win Rate 📈 The MACD and RSI strategy combines two momentum indicators to help identify potential trading opportunities. By adding a third indicator as a mean reversion filter, we can build a rules-based strategy and test how it performs. We backtest the following trading approach: ➤ We combine MACD and RSI with a third indicator as a mean reversion filter. ➤ When all three conditions are met, we buy. ➤ We exit when the mean reversion filter reverses, triggering the opposite of the entry condition. The rules are simple, but the results look promising. The strategy works best on stocks within a specific sector. Below is the equity curve for the strategy applied to an ETF. The backtest produced 169 trades, with an average gain of 0.62% per trade. Most years were profitable, while losing years showed relatively small losses. The worst year was 2008, with a loss of just 3.6%, compared with a 55% decline in the S&P 500. Can the strategy be improved or tested with different rules? If you have any suggestions, please comment 👇 #TradingStrategies
    Download
    327710.5K
  13. Сarm1ne✓@carm1nee
    this repository is f*cking BROKEN goldman sachs pays each quant up to $300k a year, all thanks to this repo It's called gs-quant, developed and maintained by Goldman Sachs' own quant team, and it already has 13.5k stars First, get how it works: 1. Goldman Sachs' quants built this toolkit on 25 years of their own risk experience: pricing, risk, backtesting, swaps, swaptions, FX options, timeseries - all in there. It even ships a skill that teaches Claude Code how to use it. 2. Every time Claude writes gs-quant code, it runs Goldman's risk math right in your notebook: volatility, drawdown, z-score, beta, RSI. 3. Pair it with Machine Learning for Trading (21.6k stars) - 27 chapters that take you from data sourcing to live execution. Together it's the exact stack a quant interview tests. Here's how you can run it for free yourself: 1. Open Claude Code, install Goldman Sachs' library: pip install gs-quant 2. Add the skill: python -m gs_quant.skills install --global 3. Have Claude pull 5-year daily prices for GS and SPY with free yfinance data 4. Run Goldman Sachs' risk math on it: volatility, max drawdown, z-score, Bollinger Bands, RSI 5. Check 60-day beta and correlation to SPY. Is it the stock moving, or the whole market? 6. Mark every day the z-score drops below -2. That means the price is 2 standard deviations below normal 7. Backtest a rule: buy below -2, sell when back at 0, including fees. Claude writes the code and runs it 8. Walk-forward it the ML4T way. If it doesn't beat buy-and-hold after fees, it's not an edge i won't say anything more:
    Download
    Сarm1ne @carm1nee
    these 10 GitHub repos are the most DANGEROUS thing in trading right now together they give you a full AI hedge fund: a research desk, an investment committee and an execution desk in this article I've shown EXACTLY how to build it from scratch
    206943238.3K
  14. Hunid Capital@hunidcapital
    A Perfect Backtest Can Be a Terrible Strategy: Overfitting Explained | 032 A perfect backtest can be a terrible strategy. Fitting is not prediction. Keep a sealed test set. Touch it once. #AlgoTrading #Backtesting
    Download
    10246
  15. Luca - Cryptic Trades✓@CrypticTrades_
    This $BTC pullback is just a BULLISH BACKTEST. My first upside target remains $93K. Nothing changed.
    Download
    771859.8K
  16. BHARATH NANDA | Algo Trading✓@AlgoWithBharath
    Your first algo, in 5 steps: a moving-average crossover. Pick an instrument, compute 2 SMAs, write the rule, backtest with costs, add risk limits &amp; paper trade. Hypothetical example. #AlgoTrading #Backtesting Education only, not investment advice.
    Download
    00017
  17. Nullbar@nullbarlab
    The largest crypto hack on record happened yesterday. About $6.3–6.4B left Binance hot wallets in minutes. Here’s what’s known so far, with sources. 🧵 #Binance #Crypto
    Download
    20026
  18. Nullbar@nullbarlab
    @nullbarlab
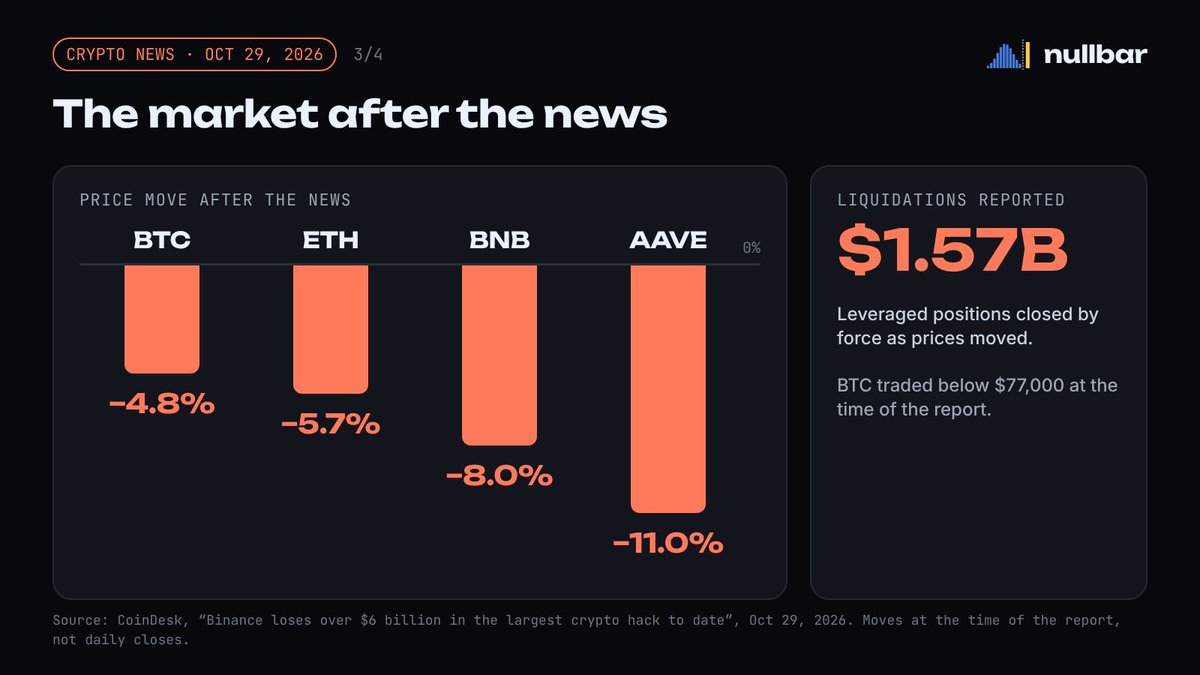
    The market: • BTC −4.8%, ETH −5.7%, BNB −8% after the news • About $1.57B in liquidations reported If you trade perps with leverage, days like this are where stops slip and liquidations cascade. bitcoin:native ethereum:native binancecoin:native
    Download
    1009
  19. Nullbar@nullbarlab
    @nullbarlab
    Our angle: most backtests never include a day like this. A rule that looks fine on calm data can break on one shock day. Test your strategy on the bad days too. Beat the null. Or know you didn’t. #Backtesting
    Download
    0004
  20. TOGI✓@ShaneStoffer
    FDs are brutal. I’m not sure what I was supposed to learn here but something was probably learned
    Download
    411241.1K324K
  21. KC Trades✓@KCTrades777
    @ShaneStoffer
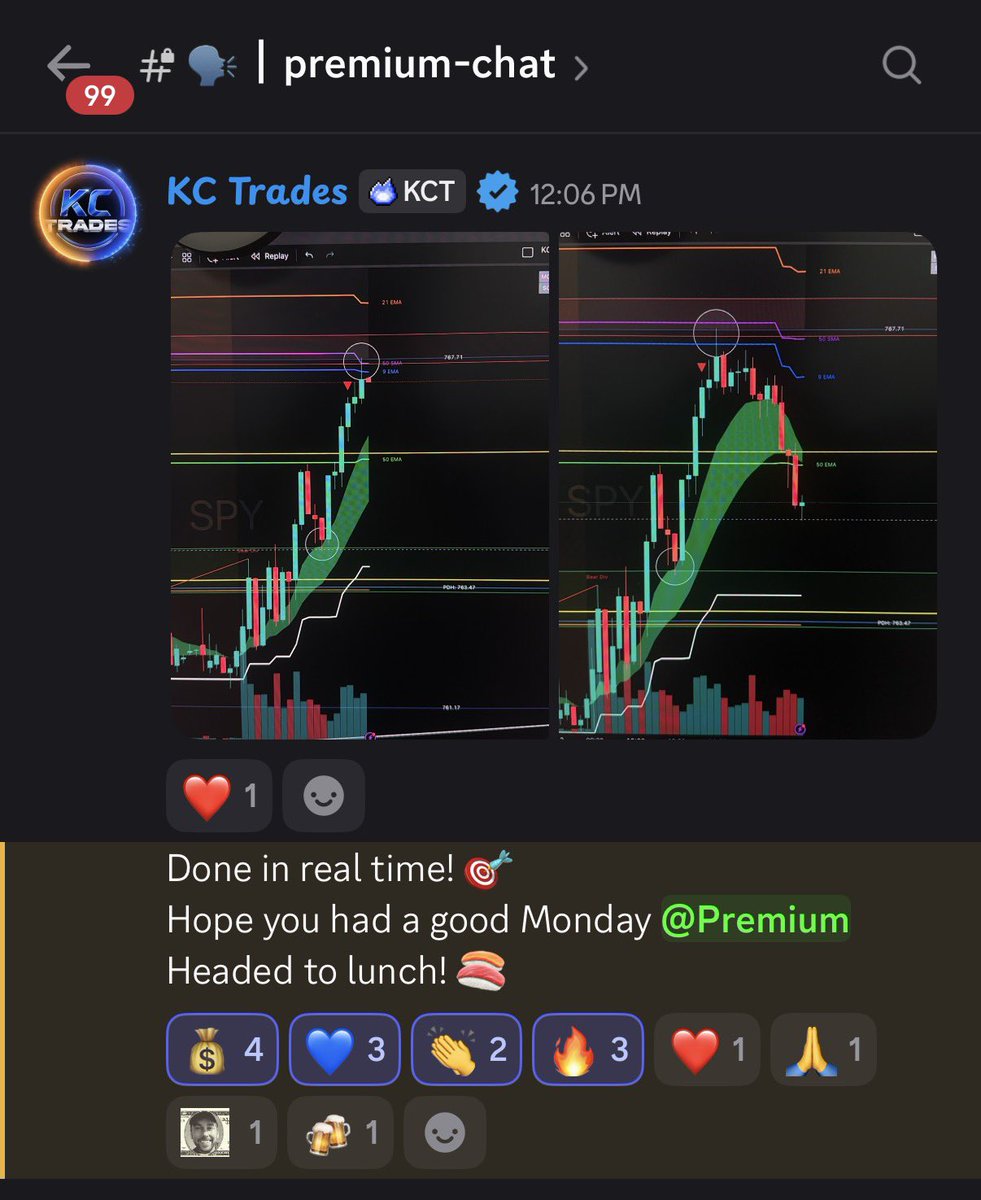
    @ShaneStoffer $SPY backtest the Daily 9 and 50 SMA, also lined up with previous session high on Thursday where it sold off as well. Great setup for a short setup for puts there. If you want to learn more just send me a DM and we can bring you up on livestream 😁
    Download
    30113.4K
  22. Сarm1ne✓@carm1nee
    🚨 these 3 github repos are the most POWERFUL trading combo i've ever seen Hedge funds pay analysts, traders and risk teams millions a year. These 3 repos turn that whole team into AI agents you can run for free It's TradingAgents, ai-hedge-fund and freqtrade, with 238k+ stars combined. First, get how it works: 1. TradingAgents is a multi-agent framework that mirrors the dynamics of real-world trading firms: fundamental, sentiment, news and technical analysts write reports, bull and bear researchers debate them, a trader decides and a risk team signs off. 2. ai-hedge-fund is a proof of concept for an AI-powered hedge fund: agents modeled on investors like Warren Buffett, Charlie Munger, Michael Burry and Cathie Wood each give a signal, then a risk manager and a portfolio manager make the call. 3. freqtrade is the free, open source trading bot that turns a signal into a strategy, with backtesting, hyperopt and a dry-run mode that trades on paper first. Here's how you can run it for free yourself: 1. Open Claude Code and clone the 3 repos: TradingAgents, ai-hedge-fund and freqtrade 2. Run TradingAgents' CLI with python -m cli.main and pick a ticker 3. Watch the analyst team write its reports, the bull and bear researchers argue, and the trader and risk team land on BUY, SELL or HOLD 4. Install ai-hedge-fund with pipx install aihf and run it on the same tickers. Every investor agent returns a signal and a confidence 5. Have Claude merge both: only act when TradingAgents and the investor agents agree 6. Have Claude turn that merged signal into a freqtrade strategy 7. Backtest it in freqtrade on 2 years of data, fees included 8. Tune it with freqtrade hyperopt, then re-test on data it never saw so you don't fool yourself with overfitting 9. Run it in dry-run mode for 2 weeks. If it doesn't beat buy-and-hold after fees, it's not an edge yet i won't say anything more:
    Download
    Сarm1ne @carm1nee
    these 10 GitHub repos are the most DANGEROUS thing in trading right now together they give you a full AI hedge fund: a research desk, an investment committee and an execution desk in this article I've shown EXACTLY how to build it from scratch
    152317912.1K
  23. AlphaPrime@AlphaPrimeGPU
    US clocks fall back tonight. If your backtest session is set in Eastern time but your data is stamped in another time zone, the session window shifts by an hour for part of the year. Worth checking before Monday. #futures #backtesting #ES_F #NQ_F
    0002
  24. Yuniel@yunielap
    Factor de beneficio de 1,97 en entrenamiento. Fuera de muestra: 1,86. Una estrategia ORB con gap alcista en PCVX que aguantó con datos que no había visto, aunque la tasa de acierto bajó del 56,7% al 38,5%. Curva y cada operación 👇 #backtesting…
    0005
  25. Public✓@public
    Before you put a trading strategy to work, put it to the test. Build a backtest with the Public API and Python—from pulling historical market data to evaluating the results. Here’s how:
    15164.3K
  26. QuantifiedStrategies.com✓@QuantifiedStrat
    Best Day Trading Strategies: Most day traders use intraday data for backtesting and trading, such as 5-minute or hourly bars. But in this example, we’ll use daily bars instead. The reason is simplicity — daily bars are much easier to backtest and trade. In many cases, day trading with daily bars can be a smarter approach! We backtest the following trading rules: ➤ We short at the open on the last trading day of each month (not the calendar day, but the actual trading day). ➤ We cover at the close. We backtest the Russell 2000 futures (@RTY) from 2000 through the end of 2021, using 2022 as our out-of-sample test period. We use trading hours from 08:30 to 15:00 Chicago local time. Here’s how the strategy performed through 2022 (shown below). Can we improve the strategy or test some variations? If you have any suggestions, please share them in the comments! 👇
    Download
    50101.7K
  27. Show more posts