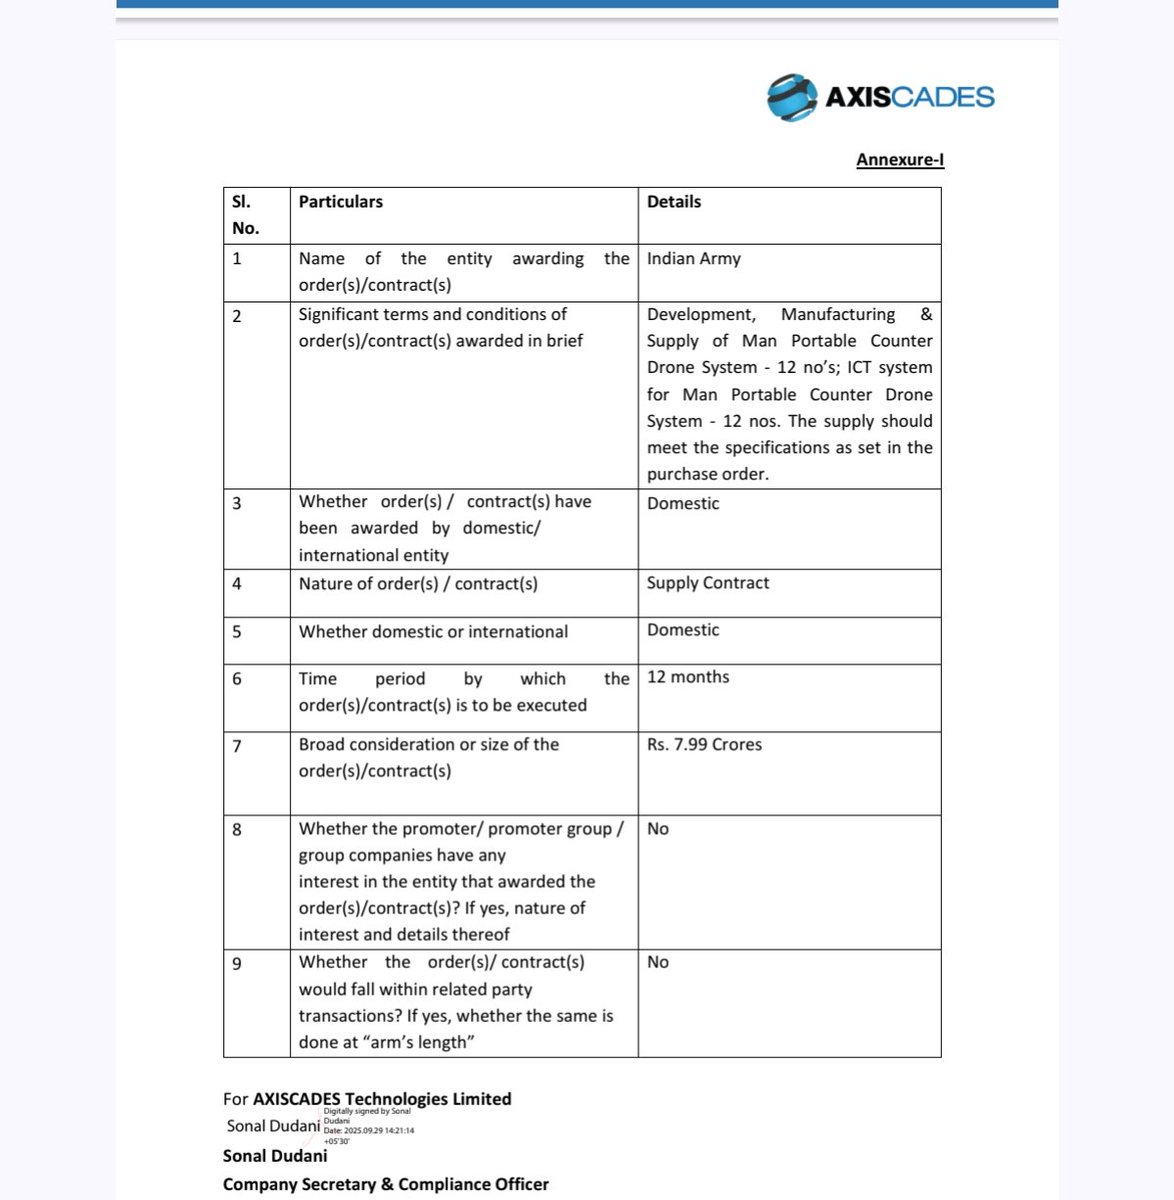
AXISCADES Q1 FY26: Company on the right track, Future looks strong
>>Revenue: 244 (+9% YoY)
>>EBITDA (reported): 34 | 14.0%
>>EBITDA (normalized): 34 (+86% YoY vs normalized base; +582 bps margin to 14.0%)
>> PAT: 21 (8.2% margin; +25% YoY)
>> H2 weighting: ~65% of FY26 revenue expected in H2 (defence execution ramp).
Domain Wise Performance:
Core (Aerospace, Defence, ESAI) – focus growth
>> Revenue: 182 | EBITDA: 34 (18.6%)
>> Aerospace: Rev 85 (+7% YoY), EBITDA margin 17.3%
>> Defence: Rev 59 (+22% YoY), EBITDA margin 18.6%
>> ESAI: Rev 38 (+34% YoY), EBITDA margin 21.6%
>> Other (HE & Auto, Energy) – reset/profit focus
>> Revenue: 61 | EBITDA: ~0.3 (0.5%)
>> HE & Auto: Rev 50, EBITDA −3.4%
>> Energy: Rev 11, EBITDA 18.1%
Operating Geography:
>> USA 32% | Europe 37% | Canada 4% | APAC 27%.
>> Delivery: Offshore 77% / Onsite 23%
>> Contract type: T&M 69% / Fixed-price 31%
Not a buy/sell recommendation
#AXISCADES #Q1FY26 #Earnings #Defence #Aerospace #EngineeringServices #Semiconductor #MakeInIndia #AtmanirbharBharat #LongTermInvesting