Posts with #impliedvolatility

#impliedvolatility

Public posts on X that use #impliedvolatility.

Related hashtags

  1. tastylive✓@tastyliveshow
    A high IV number doesn’t always tell the whole story. @TraderMikeyB explains why one volatility spike can distort IV Rank, and how IV Percentile can give traders a clearer read on whether options are actually expensive. #Options #ImpliedVolatility
    Download
    12152.9K
  2. Sam Perez✓@sperezintexas
    Last night's earnings scorecard: options priced the size, not the direction. $APP 1-sd ~±18.5% (SquawkFlow) → ~+20% premarket $QCOM ~±8.9% (TipRanks) → ~-9 to -11% this AM $ARM ~±11-12% → ~-7% (CNBC, 24/7 Wall St, Yahoo) 🧵
    10048
  3. Sam Perez✓@sperezintexas
    @sperezintexas
    Tonight AMC: $IREN ±16.4%, $SOUN ±14.1%, $NET ±14.0%, $TEAM ±13.9%, $ABNB ±7.1% (TipRanks, MomentumSift). The straddle price is the breakeven. $ABNB's ~$12.53 ATM straddle (SquawkFlow): a buyer needs a bigger move than that by Friday; a seller keeps it but owns the tail.
    100138
  4. Sam Perez✓@sperezintexas
    @sperezintexas
    After the print the event premium drains out (IV crush). Right on direction can still lose if the move is smaller than what you paid. Size to the priced move, not the hunch. Educational, not financial advice. #Fintech #Options #ImpliedVolatility #Earnings
    0008
  5. Interactive Brokers@IBKR
    If a stock with 20% #impliedvolatility moves 7% in a day, is that normal? The Rule of 16 transforms annualized #volatility into daily expectations, giving traders a much clearer framework to evaluate price action: *Options involve risk, visit link.
    121911.9K
  6. Sunita@SunitaDiaries
    Buying options during high IV events might yield the right direction but still result in a loss due to IV crush. Understand Option Greeks—knowing when to buy options is just as critical as knowing what to buy. #OptionGreeks #ImpliedVolatility #OptionsTrading #BankNifty
    00012
  7. Sam Perez✓@sperezintexas
    Same Monday, two very different prices on uncertainty. $AAPL options price about ±4.3% into today's report. $PLTR, about ±13.3% (TipRanks, Barchart). Roughly 3x the priced swing for PLTR. That's the market charging for uncertainty, not calling direction. 🧵
    10038
  8. Sam Perez✓@sperezintexas
    @sperezintexas
    Why it matters for sizing: a ±13% priced move means the same position carries ~3x the expected swing of a ±4% one. Equal share counts aren't equal risk. Scale size to the priced move first, then decide on direction, if you have one at all.
    1005
  9. Sam Perez✓@sperezintexas
    @sperezintexas
    After the print, uncertainty resolves and IV usually falls hard (IV crush). Long premium needs a move bigger than what was priced just to break even. Context-aware ideas with rationale: Not financial advice. #Options #Fintech #ImpliedVolatility #Earnings
    0005
  10. Catalyst Traders✓@CCatalyst_2
    1W #ImpliedVolatility dropped from ~56% to ~50% — traders pricing less immediate risk and panic hedging fading 📉💪. Market moving from stressed and reactive to calmer and more stable 🔴.
    Download
    10048
  11. TonyMezzoretta@tonymezzoretta
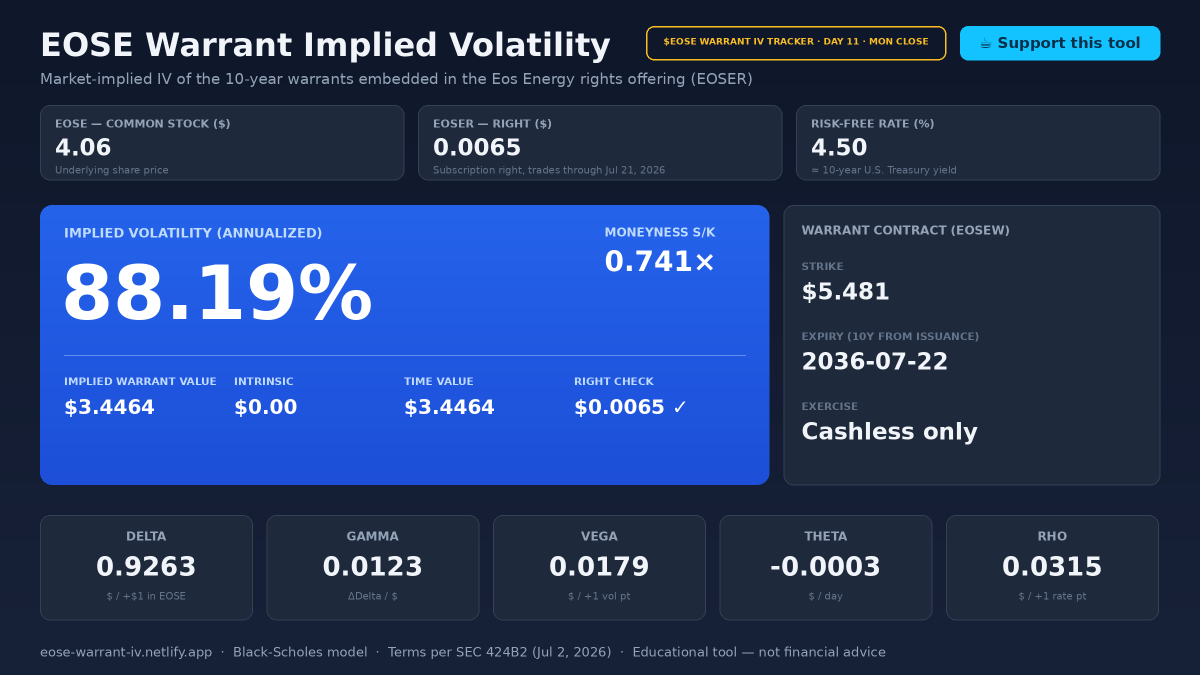
    Monday close: $EOSE $4.060, $EOSER $0.0065 → implied warrant vol 88.19%. Basically flat from this morning's 89.25% open — first quiet session in two weeks. One trading day left. #ImpliedVolatility #OptionsTrading
    Download
    30111.4K
  12. Felipe Adan Lerma@FelipeAdanLerma
    PLUNGING RATES SEND #STOCKS SOARING AHEAD OF A BUSY WEEK excerpt - "The problem, as mentioned over the weekend, is that once the company (#Nvidia) reports, those calls will plunge in value, so unless the company surprises, meaning...." -Mike Terms By Gemini #ImpliedVolatility (IV)- A metric that reflects the market’s forecast of a likely movement in a security’s price. It is a key input in options pricing models, indicating how much uncertainty or risk the market associates with future price changes. Higher IV usually means higher option premiums" @MichaelMOTTCM
    Download
    3153.6K
  13. Felipe Adan Lerma@FelipeAdanLerma
    "The issue is that implied volatility is unusually high for #Apple, causing premiums on puts and calls to become elevated. After the company reports results, #impliedvolatility will collapse, leaving market makers over-hedged. As a result, they’ll need to sell Apple shares to rebalance their positions. This places Apple in a situation where, regardless of earnings or guidance, the stock is likely headed lower" BULLISH OPTIONS POSITIONING SETS HIGH BAR FOR THIS WEEK’S EARNINGS @MichaelMOTTCM #StockMarket
    Download
    24185.1K
  14. Show more posts